Prices
October 19, 2014
Line Pipe Dumping Filed Against Turkey & South Korea
Written by Peter Brebach
US pipe producers filed dumping and countervailing duty petitions on Line Pipe against producers in Korea and Turkey, alleging dumping margins of 16 percent against Turkey and from 58 percent to 221 percent against Korea (the alleged CVD margins are not known or not published at this time).
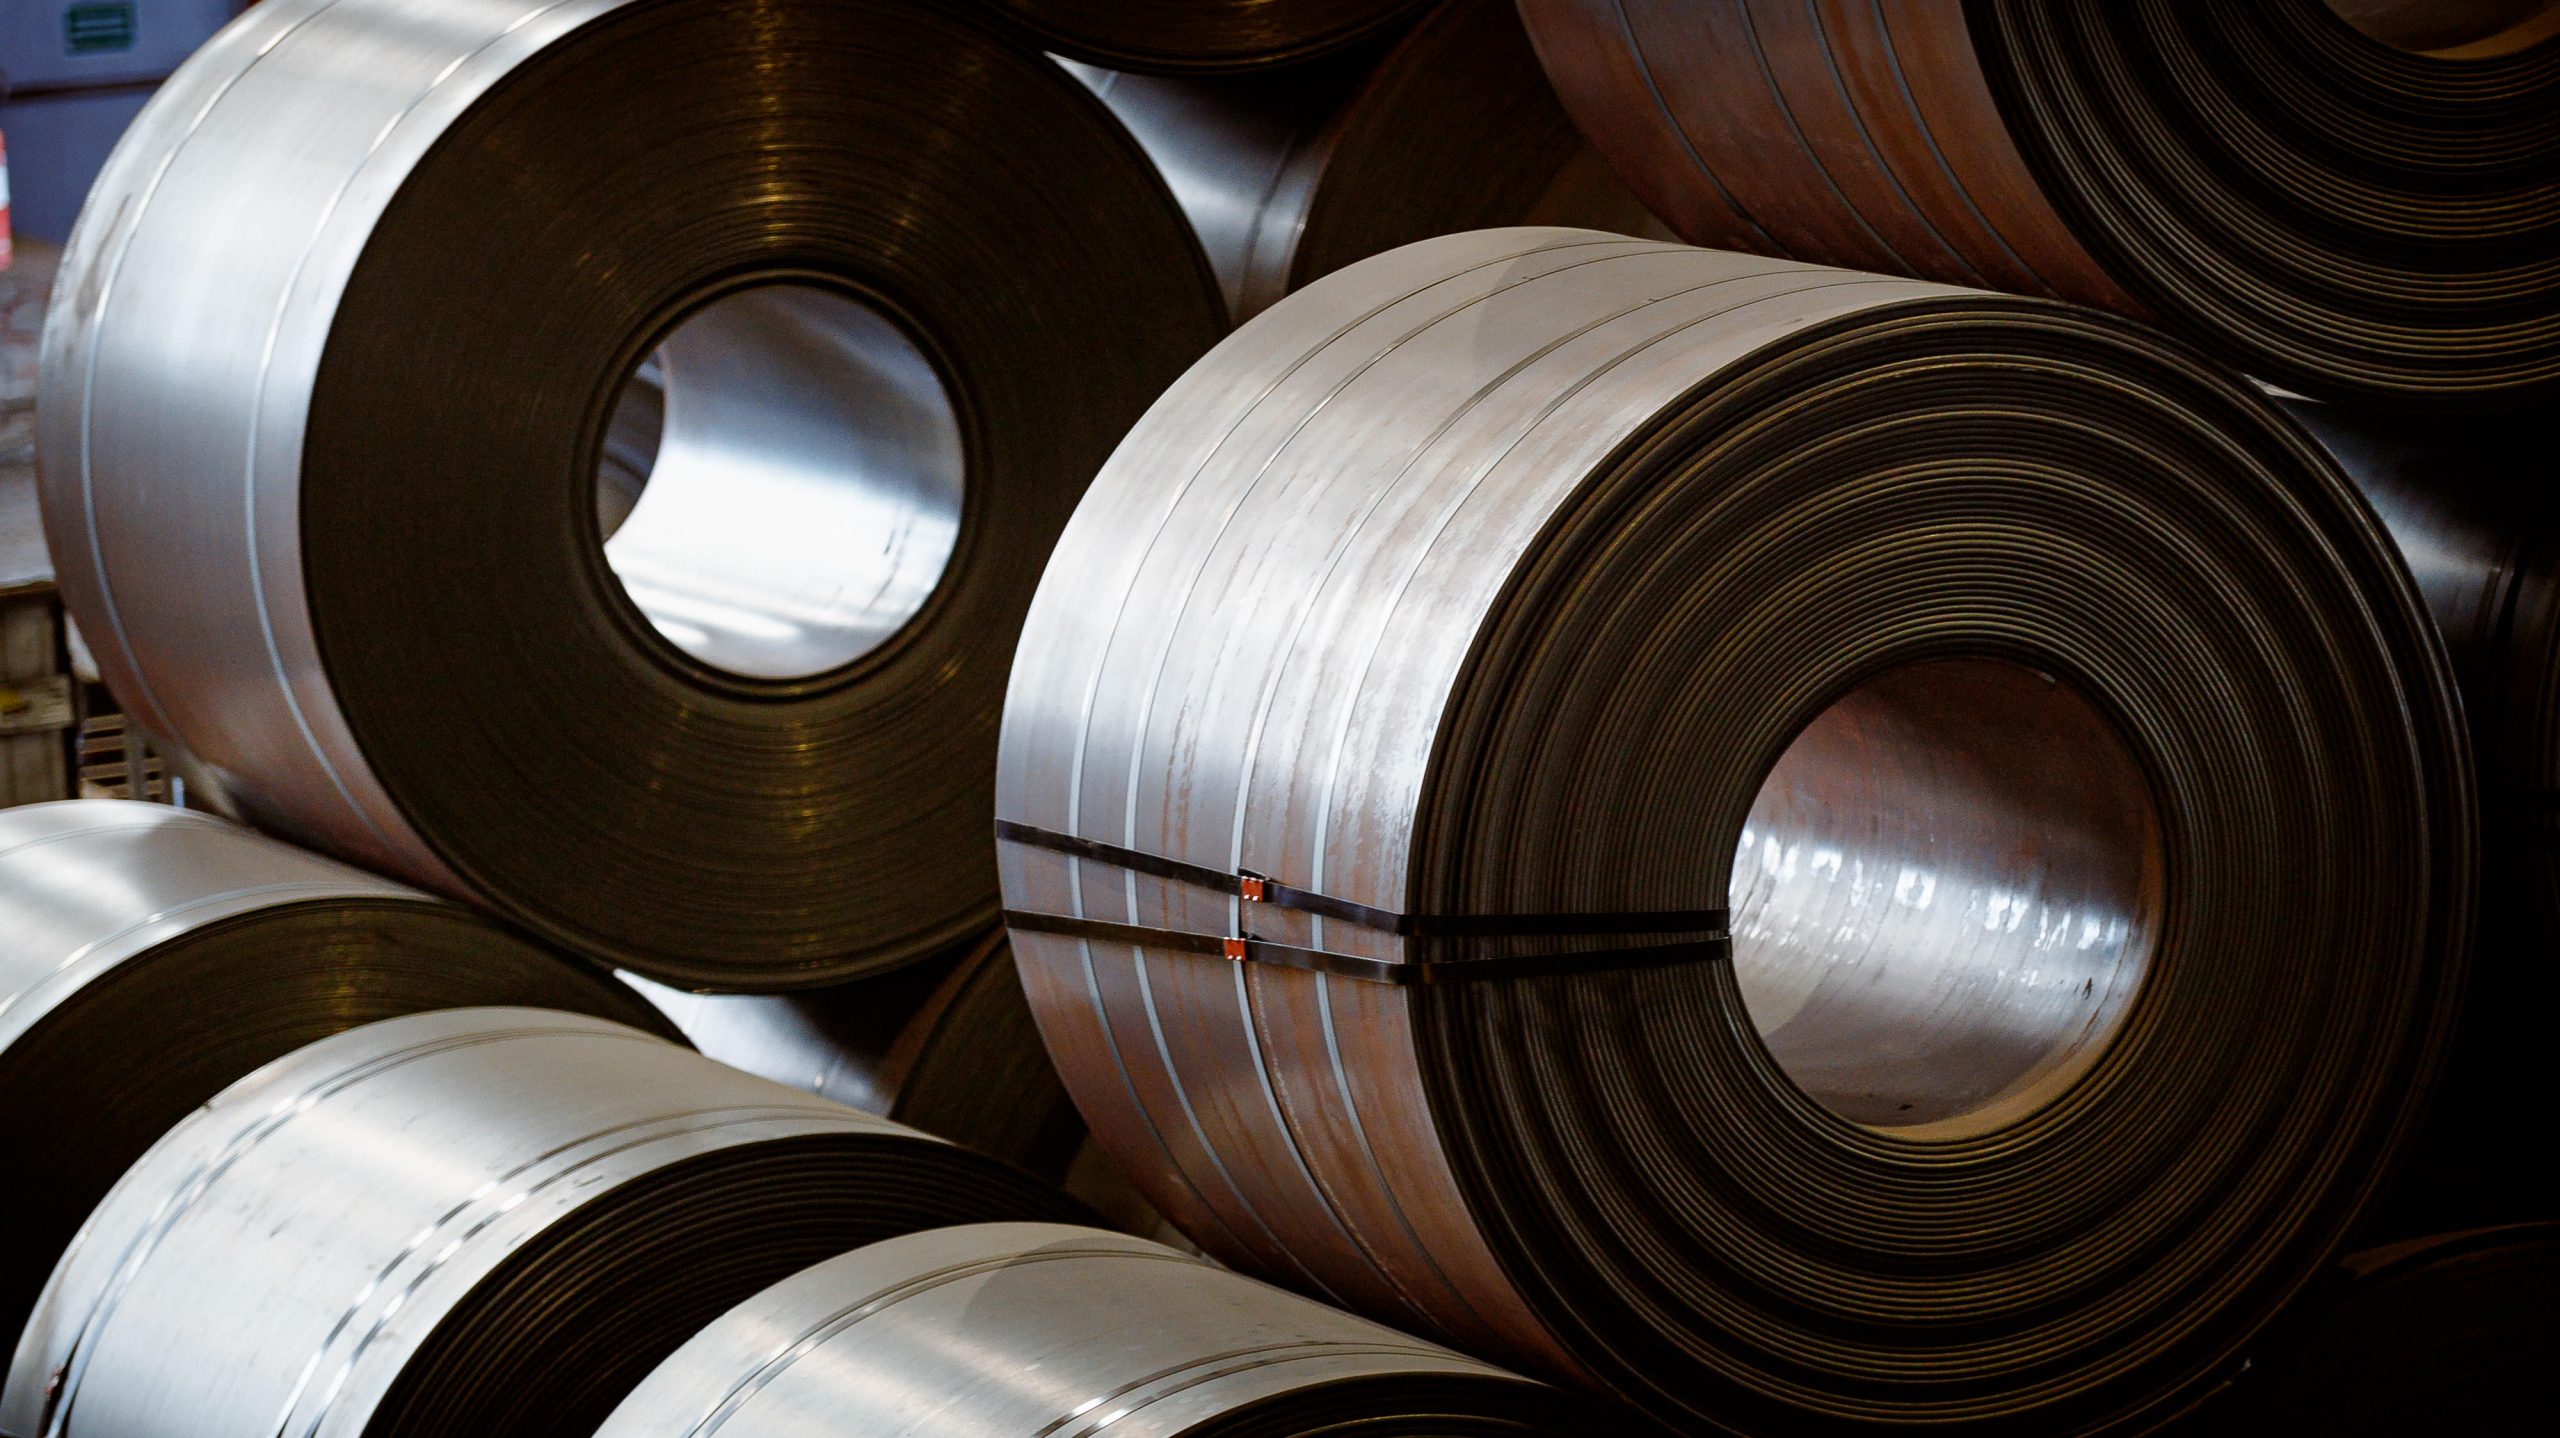
This comes relatively shortly after the trade case on OCTG was completed, mostly successfully. For the better understanding of those not active in the pipe business, OCTG are used vertically (down-hole), while Line Pipe is used horizontally. Another difference is that the vast majority of line pipe is “welded,” while a good portion of OCTG is “seamless.” That also means that practically all the raw material for line pipe is hot rolled coil, while some for OCTG is not (seamless pipe requires round billets).
 There is a certain amount of overlap between these two products, i.e. mills that produce one can usually produce the other. However, OCTG are a bit more demanding and thus more difficult to produce than line pipe.
Line Pipe is generally used for the conveyance of oil and gas, and the recent shale drilling boom in new fields, like the Bakken in North Dakato, the Eagle Ford in Texas and the Marcellus in Pennsylvania, has increased the domestic production in these areas without a lot of line pipe infrastructure. And while one can transport oil by rail or truck, if necessary, that is not possible with gas. The result is that the demand for line pipe in the US has increased substantially. However, to the detriment of the US producers, the market share of imports has continued to go up, preventing the local mills from enjoying this windfall.
The domestic market is somewhere between 3 and 4 million tons annually, and imports have enjoyed a share of over 50 percent for some time. However, the mills that were hit with OCTG margins, and thus precluded from OCTG exports to the US, are expected to shift some of those lost volumes into line pipe.