• Skip to main content

    Tag: demand

    Reliance posts big Q3 profit on high prices, border-wall demand

    Reliance Inc. posted a third-quarter profit more than double that of a year ago on record quarterly sales. The stellar result came thanks to higher steel prices and a jump in tons sold. A government contract for the US border wall with Mexico drove a significant portion of those gains, the company said. And the Phoenix-based service center chain, North America’s largest, predicted that profits would continue to surge in the fourth quarter despite concerns about steel availability and geopolitical instability.

    Steel market chatter this week

    The majority of buyers SMU polled this week expect prices to continue rising from here, supported by limited supply. Demand is said to be strong, with most remarking that it is stable to improving. Most say inventories are moving faster this year than last, attributed to tight supply, late mill deliveries, and generally leaner supply chains. Imports continue to appeal to many buyers on both price and availability, but lead times, tariffs, and other risks remain. Buyers are split on whether President Trump’s tariff policies are helping their businesses and whether they’re seeing manufacturing reshoring.

    Commercial vehicle pullback weighs on North American auto output

    North American auto assemblies fell 2.2% from August to 1.314 million units in September, as lower commercial vehicle production outweighed nearly unchanged personal vehicle output, according to GlobalData. After steady gains through Q2, automotive production has been inconsistent, continuing a seesaw pattern. Still, assemblies remain muted and well below pre-pandemic levels. Total production was 4% below September 2025. Still, last month’s production total was 2.7% above 2026’s monthly average of 1.28 million units.

    Fed Beige Book finds stronger steel, machinery demand but rising cost pressure

    Manufacturing activity improved in several Federal Reserve districts, but conditions remained mixed nationwide, according to the Fed’s Oct. 14 Beige Book report. Demand was strongest in steel, machinery, defense-related products, and data center infrastructure. Steel producers in the Cleveland District reported firm spot market demand. Data center, power-generation, defense, and aerospace projects supported orders. Long mill lead times kept customer inventories lean and prices high. Producers also reported higher orders from truck-trailer and light-vehicle manufacturers. International demand for hydrogen vehicle parts increased.

    SMU flat-rolled market survey results now available

    The results of the latest Steel Market Update (SMU) flat-rolled market survey are now available on our website to all premium members. After logging in, look under the Data tab for Market Reports, and there you will find the Flat-Rolled Survey Results section. Previous survey results are also available on that page. If you need help accessing these results, or if your company would like to have your voice heard in our future surveys, contact smu@crugroup.com.

    Apparent steel supply remains historically strong through August

    The volume of finished steel that entered the US market increased 1% from July to August to the second-highest monthly level recorded in the past four years, according to SMU’s analysis of recently released Department of Commerce and American Iron and Steel Institute data. Apparent steel supply is calculated by combining domestic mill shipments and finished US steel imports, then subtracting total US exports. It can be used as a proxy for domestic steel demand. Supply has remained historically strong since May, when it surpassed the 9 million st mark it had previously been beneath for four years.

    worldsteel expects steady global steel demand in 2026, growth in 2027

    The World Steel Association (worldsteel) forecasts flat steel demand in 2026, as contraction in China and disruption in the Gulf region offset growth in India and other markets, including the US. Global demand is expected to rise slightly in 2027. The Brussels-based association’s Short Range Outlook (SRO) for 2026 pegs global steel demand at 1,722 million metric tons (mt), essentially unchanged from 2025. For 2027, worldsteel forecasts 1.7% growth to 1,752 million mt. “The trajectory we set out in April holds, but the anticipated recovery is proving slower and more gradual than we had expected,” commented Alfonso Hidalgo de Calcerrada, chair of the worldsteel Economics Committee. “Global steel demand is now forecast to be flat in 2026 rather than to grow modestly, and to grow by 1.7% in 2027 rather than 2.2%. Almost the whole of that revision is a China story,” Calcerrada added.

    Steel market chatter this week

    Steel market chatter this week Earlier this week, SMU polled steel buyers on an array of topics, ranging from market prices, demand, and inventories to tariffs, imports, and evolving market events. We are sharing a selection of the comments we received below, in each buyer’s own words. Before diving in, we reviewed all of the responses collected and compiled these key takeaways: • Most buyers continue to expect higher prices in the near future and report that demand is stable to improving. • Inventories are moving faster than they were this time last year for most respondents, attributed to limited availability and leaner supply chains. • Imports are attractive for many buyers on both price and availability, though quotas, long lead times, and quality concerns continue to limit their appeal. • Buyers were split on whether tariff policies are helping their businesses, while a slight majority reported some evidence of manufacturing reshoring, though many said it is still too early to tell. Want to share your thoughts? Contact david@steelmarketupdate.com to be included in our market questionnaires. How do you expect prices to trend over the next three months? “I expect prices to rise at a fairly rapid pace for at least the next two to three months because inventories will continue to decrease.” “Upward, capacity remains tight.” “Climbing for several months.” “Trending toward $1,300/st HRC, only because one small player is driving prices up with no one else selling spot.” “Higher, the Q1 bump is not showing in the futures market.” “We expect things to keep going up from here. Next year could get ugly, but we're not there yet.” “Still trending up. There are some soft spots getting softer, but still steady demand and a shortage of supply.” “Continue to rise slowly.” “Slow increases like they have been doing.” “Upward due to continued demand and mill maintenance outages.” “Will remain high but steady due to demand and tariff implications.” “Plate prices most likely will be flat to up over the next three months.” Is demand improving, declining or stable? “Demand is stable (if anything, overstated), with inventories so lean, late mill deliveries, and contract prices increasing next year.” “Demand is fairly consistent with the rest of the year.” “Stable, but very strong for our products.” “Stable as many projects are trying to get ahead of potential additional price increases.” “Stable due to the ‘slow season’ in our market.” “Plate demand is stable to improving.” “Demand is good to improving. We'll take it!” “Improving, but still not to 100% capacity.” Is inventory moving faster or slower than this time last year? “Faster... once it arrives (late), it goes right back out.” “Faster due to lack of availability and bullwhip buying.” “Inventory is moving faster this year than last because demand is stronger than last year and many of our competitors don't have as much steel to offer.” “Inventory is moving faster with supply chains so lean.” “Inventory is moving at a good clip. Just based on costs/spends, we're stocking less sheet, coil and plate though.” “Plate inventory is moving at a much faster pace year over year due to several factors.” “Faster due to a shortage of supply plus added demand.” “About the same.” Are President Trump's tariff policies helping your business? Buyers were split this week, with 44% believing the tariffs are helping their business and 44% saying they are not. The remaining 11% were unsure how the policies will impact them. Comments included: “Yes for now. Prices are very high, which causes people to buy before prices get higher.” “Yes, I credit Trump's policies and data centers for improving demand.” “Yes, inventory values continue to go up.” “They are helping on the sell side and hurting on the buy side.” “No, they are creating shortages and increasing the cost of steel.” Are you seeing evidence of manufacturing reshoring to the US because of Trump's tariffs? The slight majority of respondents (39%) reported they have seen some evidence of reshoring, a higher rate compared to recent surveys. A third said it is too early to say, and 28% answered they are not seeing any signs of reshoring. Comments included: “Yes. Perhaps reshoring has added to the increased demand in 2026.” “Yes, with machining and turning.” “Yes, capacity versus demand in North America is creating pressure to reshore products.” “Too early to say. There have been a lot of announcements, but steel availability has limited immediate moves.” Are imports more attractive than domestic material? “Imports are more attractive on a pricing front and an availability standpoint, but lead times are extended.” “Imports are attractive in both price and because they offer additional availability. Whether or not they show up and or as offered is another issue.” “Imports are certainly attractive. They're coming in in earnest, so this run will peter out early next year.” “Attractive due to price and availability.” “Attractive, domestic tons are unavailable.” “Yes on light gauge painted.” “Without quotas, yes, the price is more attractive. But if you get caught with the quota, pricing is very high.” “Not to us, but we are hearing more about affordable imports.” “Plate imports are only slightly more attractive than domestically produced plate.” “Not yet, shipping lag is still too large.” “No due to tariffs.” What's something that's going on in the market that nobody is talking about? “What is the latest on SDI/BlueScope? I had heard it was back on the ‘front burner’ but all is quiet now. Maybe that means a deal is getting close?” “Will the US bring a trade case against South Korea over imports spiking?” “Busheling scrap prices are flat, while hot roll continues to rise. The scrap gap is increasing.” “How will the next administration handle tariffs that have so limited our steel supply?” “Mill discipline in production capacity.” “Coke pricing levels due to demand and supply.” “Shipbuilding.”

    Plate supply squeeze tightens as demand presses higher

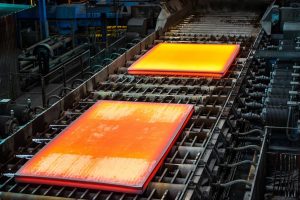
    The domestic plate market is showing few signs of relief for steel buyers. Lead times are stretching well beyond seasonal norms, spot availability has all but evaporated, and mills are drawing hard lines on contract volumes heading into 2027 negotiations. And the supply squeeze will likely intensify in a market that some industry sources say is structurally undersupplied because of stringent US trade and tariff policies. Imports have been arriving in larger volumes, and the expectation is they will continue to tick higher into 2027. The big question is whether those foreign tons will arrive in volumes sufficient to provide the relief steel consumers want.

    CRU: Global finished steel prices diverge, US the rare bright spot

    CRU: Global finished steel prices have diverged in August, with longs softening while sheet and plate firmed in most regions. Weak construction demand persisted across most longs markets, with the US the notable exception. Higher sheet prices were driven by tightening supply in the US and reduced import attractiveness in Europe, even as APAC sheet prices declined. Plate prices were mostly firmer across APAC, stable to down in Europe, and continued climbing in the US.