Analysis
July 26, 2024
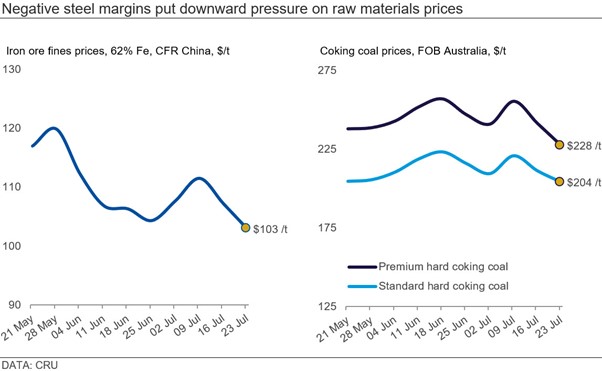
CRU: Poor steel margins continue to push down raw material prices
Written by Anh Nghiem
Both iron ore and coking coal prices fell last week because of resistance from buyers.


Analysis
July 26, 2024
Written by Anh Nghiem
Both iron ore and coking coal prices fell last week because of resistance from buyers.
In this week's Steel Market Chatter, we explore manufacturing and service center buyers' comments about demand, prime scrap, the Iran War, and expectations for Section 232 tariffs in USMCA negotiations. We'll share a selection of the comments we received in each buyer's own words. Dive in with us into the results and findings of our latest Flat-Rolled Steel Survey.
After flying into a rain-soaked London seeking answers to questions on key issues in the aluminum space, we left the city with uncertainty remaining. As always, the speakers at LME Week 2026, which ran from Oct. 19-23, did a solid job evaluating the fundamentals for each of the metals they were covering. But most shied away from providing specific price forecasts. Who could blame them given the imponderables below?
SMU’s Current Steel Buyers’ Sentiment Index ticked up slightly this week, while Future Sentiment fell, according to our latest market survey. Every two weeks, SMU polls thousands of steel-industry executives, asking them to rate their companies’ chances of success today and also three to six months down the road. We use their responses to calculate our proprietary Current and Future Steel Buyers’ Sentiment Indices, measures tracked since 2008.
The majority of steel buyers responding to our latest market survey reported that mills continue to hold a firm grip on prices. The share of buyers reporting that mills were negotiable fell this week to the lowest rate seen in over five years. Every two weeks, SMU surveys service center and manufacturer buyers asking if mills are negotiable on new spot sheet and plate orders. In this week’s survey, just 3% of respondents said mills were willing to talk price to secure an order (Figure 1). This is down 11 percentage points from our mid-October survey.
There have been some recent developments on the pig iron scene that are starting to reshape the import landscape as we round out 2026., SMU has learned. Here’s what the new import map is starting to look like in Ukraine, India, and Brazil. SMU spoke with sources commenting on each of these regions to find out the situation on the ground.