• Skip to main content

    Tag: Hot Rolled

    Sheet and plate price gains accelerate as 2026 tons dry up

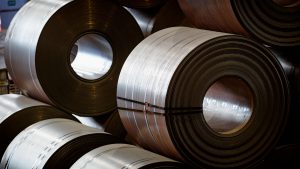
    Sheet and plate prices continue to push higher as mills charge a premium for what little spot tonnage remains for 2026, market participants said. SMU’s price assessment for hot-rolled (HR) coil now stands at $1,290 per short ton (st) on average, up $10/st week over week. HR price gains averaged $5/st w/w throughout July and August, with no changes in prices some weeks and gains of at most $15/st w/w. In September and October to date, in contrast, prices have increased every week—with the average gain at $11.25/st w/w and w/w gains as high as $20/st. Prices for cold-rolled and coated products continued to increase as well. SMU's price assessment for cold-rolled (CR) coil clocked in at...
    SMU Survey: Mill negotiation rates rise on sheet, fall for plate

    Sheet buyers found mills slightly more negotiable on price this week, while plate buyers thought mills were less flexible on spot price tags, according to our latest survey data. Every two weeks, SMU surveys service center and manufacturer buyers to see whether mills will negotiate on new spot sheet and plate orders. In this week’s survey, 14% of respondents said mills were willing to talk price to secure an order, up three percentage points from two weeks earlier (Figure 1). This is the highest reading since July 8, when the rate stood at 18%.

    US flat-rolled steel import licenses hit a 14-month high

    US flat-rolled steel import licenses climbed in September, extending a recovery after several months of depressed inbound shipments. Licenses rose 4.9% month on month to 679,889 short tons (st), their highest level in 14 months and 29.1% above the 12-month moving average (12MMA) for August, according to Commerce Department data. The increase was led by cold-rolled sheet and other metallic-coated products, with particularly sharp gains in licenses from Turkey, Taiwan, and South Korea. Hot-rolled sheet licenses eased from August’s 19-month high, while galvanized sheet, coiled plate and cut-to-length plate also slipped month on month. Even so, licenses for hot-rolled sheet and both plate categories remained elevated relative to their recent averages, pointing to continued strength across several product lines.

    Commerce updates duties on Japanese HR

    The US Department of Commerce has adjusted anti-dumping duties on imports of hot-rolled flat steel products from Japan. The adjustment has lowered duties for one company but raised them for others. Commerce made the adjustments in the final results of an administrative review of the year ended Sept. 30, 2024. The agency set a final weighted-average dumping margin of 13.96% for Nippon Steel companies. This is lower than the company’s previous rate of 29.7%.

    Nucor increases spot HR to $1,240/ton

    Nucor said on Monday, Oct. 12, that its consumer spot price (CSP) for hot-rolled (HR) coil will be $1,240 per short ton (st) this week, a $10/st increase from a week earlier. The CSP for HR coil from California Steel Industries (CSI) on the West Coast will be $1,305/st, up $15/st from the prior week. Nucor is still offering lead times of three to five weeks, according to the letter to customers. You can track mill price announcements on our website. Steel Market Update (SMU) published a weekly price assessment on Tuesday, Oct. 6, showing HR coil prices averaging $1,270/st, up $10/st from the previous week. We will update our prices on the evening of Tuesday, Oct. 13.

    Leibowitz: US steel prices skyrocket above world prices. Which are right?

    Steel markets in the United States now feature supply shortages. Spot tons are well-nigh unavailable, and even contract tons are scarce. Based on the available statistics, the US market for flat-rolled products is seriously constrained. The US economy is still the strongest in the world, and manufacturing output remains vigorous. But the available supply is tight. The reason is fairly obvious. US domestic supply has increased a bit. Meanwhile, imports have fallen significantly.

    SMU Survey: Mill negotiability rate remains at lowest level since 2021

    The vast majority of steel buyers responding to our latest market survey found mills unwilling to negotiate lower prices for spot tons. This holds true for all the products SMU tracks. Every two weeks, SMU surveys service center and manufacturer buyers asking if mills are negotiable on new spot sheet and plate orders. In this week’s survey, 9% of respondents said mills were willing to talk price to secure an order (Figure 1). This is the third consecutive survey at that rate. You'd have to go back to September 2021 to find a lower number.