SMU Survey: Mill negotiability falls to multi-year low
Steel buyers negotiation rates remain at or near historic lows across most sheet and plate products.
Steel buyers negotiation rates remain at or near historic lows across most sheet and plate products.
SMU’s average price for domestic HR was $1,145 per short ton (st) this week, $15/st higher week over week (w/w). In offshore markets last week, prices moved down, largely maintaining a trend seen since late April.
US sheet prices continue to move higher on extremely limited spot availability, solid demand, and extended lead times.
Nucor announced on Monday, June 22, that its consumer spot price (CSP) for hot-rolled coil will be $1,130 per short ton for the week, up $5/st from last week.
SMU’s average price for domestic HR was $1,130 per short ton (st) this week, $15/st higher week over week (w/w). In offshore markets last week, prices were largely down, following a trend seen since late April.
The spread between domestic hot-rolled coil and prime scrap prices continued to widen in June, a trend that began in September.
Nucor announced on Monday, June 15, that its consumer spot price (CSP) for hot-rolled coil will be $1,125 per short ton (st) for the week, up $10/st from last week.
Steel mill lead times extended this week on both sheet and plate products, now at multi-year highs.
Some domestic spot market buyers say they're seeking imported hot-rolled (HR) coils.
This week we saw continued low negotiation rates across all products, with cold rolled and plate the least negotiable and galvanized the most.
The price gap between US hot-rolled coil (HR) and landed offshore product continues to narrow, as stateside prices are now, on average, carrying a premium over imports. Domestic tags are still outpacing imported hot band as pricing dynamics diverge.
All five of SMU’s price indices increased this week to new multi-year highs. Prices have increased by 20-25% since the beginning of the year.
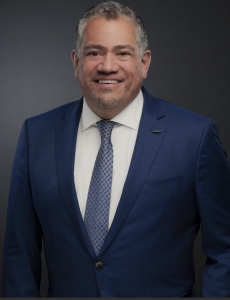
Longtime steel veteran Robert Simon is excited about the transformation taking place at JSW Steel USA. And he has a rosy outlook for the rest of the year.
Nucor announced on Monday, June 8, that its consumer spot price (CSP) for hot-rolled coil will be $1,115 per short ton (st) for the week, up $10/st from last week.
We are happy to share that the SMU Price Estimator Tool is now a little easier to navigate.
After falling to a multi-year low in March, the premium galvanized coil commands over hot-rolled (HR) coil has widened in recent months.
SMU’s sheet price indices continued to climb this week, while plate held steady, all at multi-year highs.
Participants in the hot-rolled coil spot market revealed that growing discomfort with current market dynamics hasn't deterred them from conducting spot transactions.
Steel mill lead times remain at or near multi-year highs for all sheet and plate products.
This week we saw low negotiation rates across all products, with coated and plate products slightly more negotiable than hot rolled and cold rolled.
Sheet and plate price indices increased between $5-20 per short ton (st) from last week.
Nucor announced on Tuesday, May 26, that its consumer spot price (CSP) for hot-rolled coil will be $1,095 per short ton for the week, up $5/st from last week.
Sheet prices continue to rise in a market that remains characterized by extremely limited spot availability, solid demand, long lead times, and the lowest sheet inventories since May 2021.
Nucor has increased its consumer spot price (CSP) for hot-rolled (HR) coil to $1,090 per short ton, up $10/st from last week.
Sources told SMU they’ve begun considering whether US imports of sheet might benefit the overall market.
The spread between domestic hot-rolled coil and prime scrap prices continued to widen in May, a trend that began in September.
India-based JSW Steel’s combined US operations swung to a slight profit in its fiscal fourth quarter of 2026.
SMU Survey: Sheet and plate lead times remain extended, according to buyers responding to our latest market survey.
Buyers continue to report mills are holding a firm grip on sheet and plate prices.
All five of SMU’s sheet and plate price indices ticked higher this week, rising further to new multi-year highs. Prices increased between $5-25 per short ton (st) from last week and are $30-65/st higher than they were one month ago.