Analysis
November 24, 2024
Final Thoughts
Written by Ethan Bernard
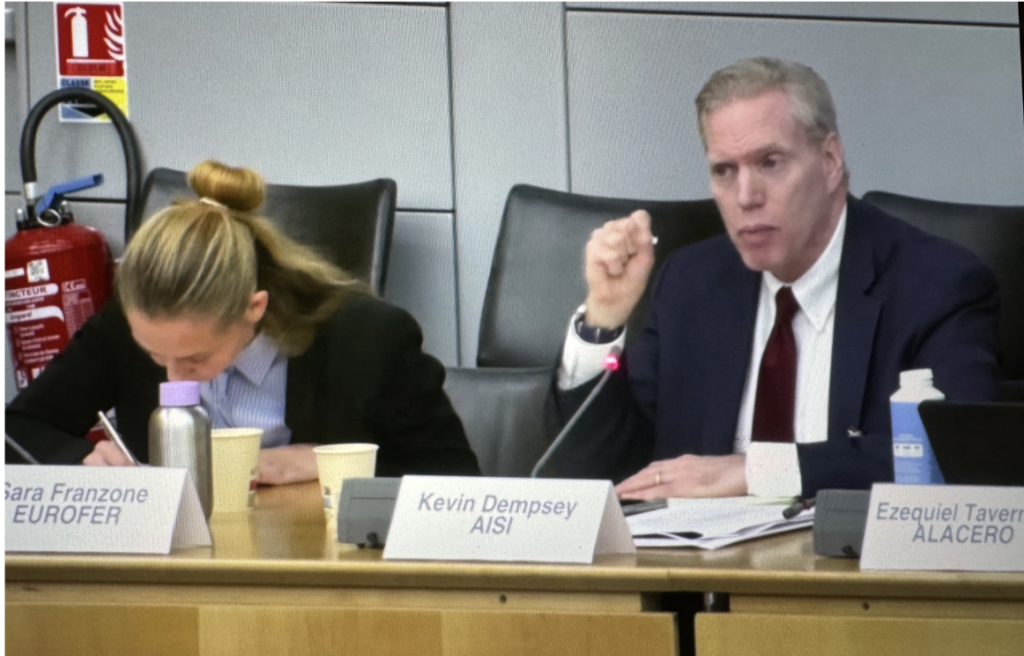
“We’ll always have Paris,” as the famous line in “Casablanca” goes. And this month, the global steel industry did as well. The Organization for Economic Co-operation and Development (OECD) Steel Committee met in the City of Lights earlier this month. There was also a meeting of the Global Forum on Steel Excess Capacity. (In reality, it was sort of a continuation of the Steel Committee meeting.) This occurred shortly after the results of the US presidential election were made known. Kevin Dempsey, president and CEO of the American Iron and Steel Institute (AISI), was on hand to participate. He gave SMU his take on what took place and his impression of the general atmosphere there following the election.
Chinese excess capacity
Front and center at the meeting was the issue of excess steel capacity in China. (It’s important to note China is no longer part of the Global Forum.)
Dempsey said that steel demand in China has been dropping because of the property/construction crisis there, but they’ve kept production steady.
“Now that demand is collapsing, they’re just exporting all their excess production, which is the current problem with excess capacity. So there’s a lot of focus on that,” he said.
While there have been big increases in Chinese steel exports to many parts of the world, that hasn’t happened in the US, Dempsey noted. That’s because we have tariffs like Section 232 and 301, as well as anti-dumping and countervailing duty tariffs.
“We have not faced the same surge in imports from China, but we are very concerned,” Dempsey said.
A convergence
The interesting thing in Paris “was how many people around the room, including the people from Europe, were very concerned about the amount of transshipment of that steel that then could end up in Europe, in the United States, elsewhere.”
A trio of issues stood at the forefront of discussion, including transshipment, circumvention, and evasion, Dempsey said, “which are each three slightly different things, but they’re all related.”
At a panel for the Global Forum, Dempsey spoke about practical solutions. He talked about how the US is collecting “melt-and-pour” data, and how Canada and Mexico are also collecting that data.
“That is a useful way to gather data that the rest of the world isn’t doing, and we had a lot of interest from Europe and others on that,” he added.
A change Dempsey noticed was that other regions are starting to raise their voices on the China situation as well.
“The fascinating thing is that you now have the South Korean industry and the Japanese industry complaining about imports from China,” he said. “So countries that have traditionally been more focused on just exporting to other regions now are really seeing the impact of the imports coming into their markets as well.”
As to whether the new convergence on this issue will yield actionable results soon, Dempsey was more skeptical.
“There’s still a lot of work to be done to get people rowing in the same direction,” he said. “I think there’s a recognition of the problem. There’s less of a common agreement on exactly how to address it.”
Election results fever?
The meeting was held Nov. 12-13. So that’s shortly after it was announced that Donald Trump would be starting a second term come Inauguration Day on Jan. 20. Was there a buzz?
“There were a lot of people on the sidelines who were very interested,” Dempsey said.
Questions included: “What’s the latest from Washington? What is the new administration going to do? Definitely a recognition that it’s not business as usual.”
He pointed out, though, that it was still before the cabinet nominations, etc., had really begun to roll in. “Murmurs just started. It had just started building,” he noted.
Despite being in the early days, Dempsey said, “I think there’s a lot of a lot of attention being placed on the expectation that there will be a big change in approach by the US government.”
He commented that on the steel policy front, there has been a lot of continuity in the Biden administration following the first Trump administration: “Biden continued a lot of the things that Trump did.”
But as far as Trump’s second term is concerned, “I think most people expect President Trump is going to ramp things up to another level.”