SMU: MOI climbs again in August, on-order pipeline expands
SMU’s Mill Order Index (MOI) accelerated in August for a fourth consecutive month, reaching its strongest reading in nearly five years.

SMU’s Mill Order Index (MOI) accelerated in August for a fourth consecutive month, reaching its strongest reading in nearly five years.
SMU’s latest Flat-Rolled Steel Buyers Survey shows that in a tight US market marked by long lead times, low inventories, and rising prices, foreign products continue to gain the interest of domestic buyers.
Service centers and manufacturers on the Sept. 15 HARDI Sheet Metal and Air Handling Council call described a tight, seller-driven market. Lead times are long, deliveries are late, inventories are thin, imports are down, and demand is strong, causing a shortage of galvanized material. SMU regularly joins the council’s meetings to discuss the galvanized sheet market. Participants — members of Heating, Air-Conditioning & Refrigeration Distributors International (HARDI) — are wholesalers, service centers, distributors, and manufacturers who buy or sell galvanized steel.
US service centers’ flat-rolled steel supply declined in August, making the marginal gain the month prior an outlier year-to-date. Shipping days of supply slipped to 44.2 in August, according to SMU data.
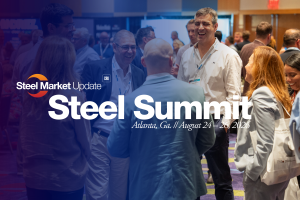
Tight steel availability and lean inventories are increasing pressure on US service centers, according to speakers on a service center panel on Wednesday, August 26, at the SMU Steel Summit 2026.
Premium Report: US service centers’ flat-rolled steel supply rose marginally in July, reversing course for the first time all year. Shipping days of supply ticked up to 45.6, according to SMU data. Service center shipments in were more than 4% below intake, noticeably trailing inbound volumes.
Foreign steel remains sharply competitive, inventory levels are mostly steady, and demand is strengthening, according to SMU's Aug. 7 market survey. But buyers are more selective than earlier in the year, even as pricing momentum continues to push spot levels higher.
SMU’s Mill Order Index 2continued to expand in June. The result came as service center on-order volumes and new order entries continue to rise, according to our latest service center inventories data.
US service centers’ flat-rolled steel supply was down marginally in June, and lower for a sixth straight month. Shipping days of supply slipped to 44.5, according to SMU data.
SMU’s Mill Order Index recovered in May, reclaiming some momentum lost the month prior.
SMU released May service center inventories on Monday. And if you’re a premium subscriber, I recommend reading the report (here) if you haven’t already.
US service centers’ flat-rolled steel supply declined for a fourth straight month in May, with shipping days of supply slipping to 44.7 on an adjusted basis, according to SMU data.
Summer doldrums? Not this year! SMU’s latest steel market survey indicates that an increasing number of steel buyers think prices will continue to rise along with the mercury.
Most companies making steel are making a lot money. And they will continue to as current high prices flow into contracts in Q3. I don’t want to kill the vibe. (No one likes that guy.) But let’s put on your risk-manager cap for a second and imagine what might keep everything from moving up and to the right indefinitely.
Steel market chatter this week: Buyers predict prices to continue rising from here, report steady to improving demand, and most see tariffs as unhelpful.
SMU’s Mill Order Index (MOI) eased marginally in April, losing some momentum after moving higher in March.
US service centers’ flat-rolled steel supply fell for a fourth straight month in April, with shipping days of supply slipping to 45.7 on an adjusted basis, according to SMU data.
SMU’s Mill Order Index (MOI) recovered in March, gaining some momentum after a marginal decline in February.
Service centers held only 2.24 months of supply (49.3 days of supply) of sheet products in March, according to our latest figures. If you check our archives, you’ll see that's the lowest sheet inventories we’ve seen since June 2021 – which was hardly a bad year for steel.
US service centers’ flat-rolled steel supply declined for a third straight month in March, with shipping days of supply slipping to 49.3 on an adjusted basis, according to SMU data.
Remember the “Got Milk?” advertising campaign of the 1990s. Maybe we should start a “Got Steel?” campaign. Or maybe “Got Spot Tons?” would be more accurate, if less catchy.
SMU’s Mill Order Index (MOI) eased in February. The result came as a marginal increase in service center intake levels was offset by higher shipments, according to our latest service center inventories data.
Sheet prices continue to inch higher. And people who once thought hot-rolled coil (HR) prices couldn’t go above $1,000 are now saying $1,100 doesn’t seem out of the question.
US service centers’ flat-rolled steel supply declined for a second consecutive month in February, with shipping days of supply slipping to 52.2 on an adjusted basis, according to SMU data.
The US steel market is already characterized by high prices and tight supplies, and I wouldn't be surprised if prices move higher and supplies get even tighter – at least in the short term.
SMU polled steel buyers on an array of topics, ranging from market prices, demand, and inventories to tariffs, imports, and evolving market events.
SMU’s Mill Order Index (MOI) rose again in January, maintaining momentum from the month prior. The increase came as service center intake levels ticked up, supported by a jump in shipments, according to our latest service center inventories data.
Premium SMU Content: US service centers’ flat-rolled steel supply declined in January, after trending higher in December. Shipping days of supply slipped to 58.5 on an adjusted basis at the end of January, according to SMU data. Flat roll supply eased in January after reaching its second-highest total for 2025 in December. The result is also a noticeable decline from 66.0 shipping days in January 2025, and a three-year low.
US service centers’ flat-rolled steel supply recovered in December, after trending lower from September to November.
The galvanized steel market has kicked off the year with a firmer tone, marked by rising prices, lengthening lead times, and a noticeable shift in buyer sentiment. Service centers and distributors on HARDI’s latest sheet metal and coil handling council call described a market that is not overheating but steadily tightening.