• Skip to main content

    Market Data

    CRU: From V to U: U.S. Recession Would Prolong Industrial Slowdown

    Written by Jumana Saleheen


    By CRU Economic Analyst Ippolito Tarabini and Chief Economist Jumana Saleheen

    World industrial production growth halved in 2019H1 to 1.5 percent from 3 percent in 2018, suffering because of a slowdown in China, the widespread downturn in the automotive sector, and the unpredictable trade negotiations between the U.S. and the rest of the world, particularly China. In response, metals demand in major economies has contracted. CRU’s base case view is that IP will modestly recover in 2020 (rising to 2 percent y/y), but the risks to our IP forecast lie to the downside. CRU’s models suggest that the probability of a recession in the U.S. and Germany is at ~40 percent, the highest it has been since the Global Financial Crisis. Recession in the U.S. would prolong the global industrial slowdown by another 12-18 months making the recovery “u” rather than v-shaped.
    Latest in Market Data

    US steel output reaches 18-year high as South leads gains: AISI

    Domestic raw steel production surged last week, reaching its highest output in almost two decades, according to the latest American Iron and Steel Institute (AISI) figures. While the seesaw pattern continued for US production this past week, production swelled to its highest reading since Aug. 23, 2008, driven by a massive swing in the South. The increase reversed the recent downward trend, with a sharp rebound in the South accounting for nearly all the weekly gain. Production has fluctuated considerably over the past two months, reaching both an 18-year high and its lowest level since January.

    Drilling activity holds in the US, moves higher in Canada

    The latest tally of active drilling rigs held steady in the US for a fourth straight week, while activity rose further in Canada this week, according to oil and gas rig count data published by Baker Hughes. The US rig count remained unchanged at 603 rigs this week, maintaining a 17-month high. Compared with this time last year, 57 more rigs are in operation today. Canada’s count rose by six to 226 rigs this week, gaining ground for a second consecutive week. Activity is up from the same week of 2025, with 39 more rigs operating today.

    HR Futures: Basic story remains, but curve shifts

    In my last column, the HRC futures curve was pricing a sizable premium on near-term tightness while still pointing toward eventual normalization. Since then, that basic story has remained intact, but the shape of the curve has shifted meaningfully. Rather than simply moving higher and pushing the peak out by another month, as has largely been the pattern throughout this rally, the curve is now pricing a more pronounced and prolonged period of tightness, while the long end has remained relatively anchored, which previously had also been lifted with the rest of the curve.

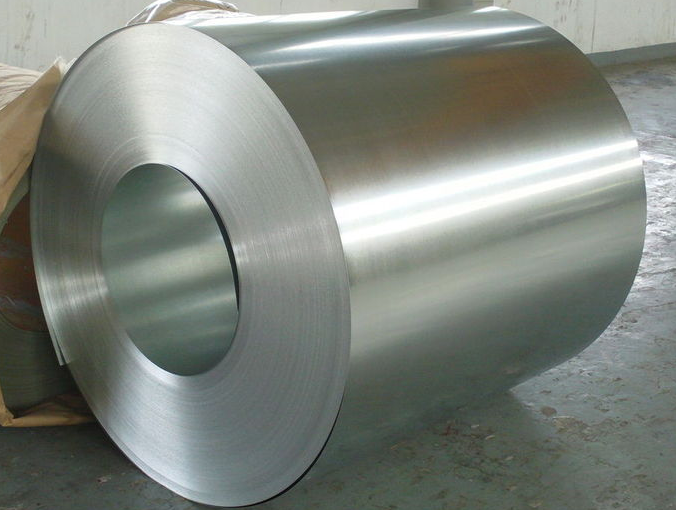
    galvalume steel coil

    SMU Survey: Mill willingness to negotiate price at lowest levels since 2021

    The majority of steel buyers responding to our latest market survey reported that mills continue to hold a firm grip on prices. The share of buyers reporting that mills were negotiable fell this week to the lowest rate seen in over five years. Every two weeks, SMU surveys service center and manufacturer buyers asking if mills are negotiable on new spot sheet and plate orders. In this week’s survey, just 3% of respondents said mills were willing to talk price to secure an order (Figure 1). This is down 11 percentage points from our mid-October survey.