• Skip to main content

    Sheet

    Section 232 curbs US CRC price gains over imports

    Written by David Schollaert


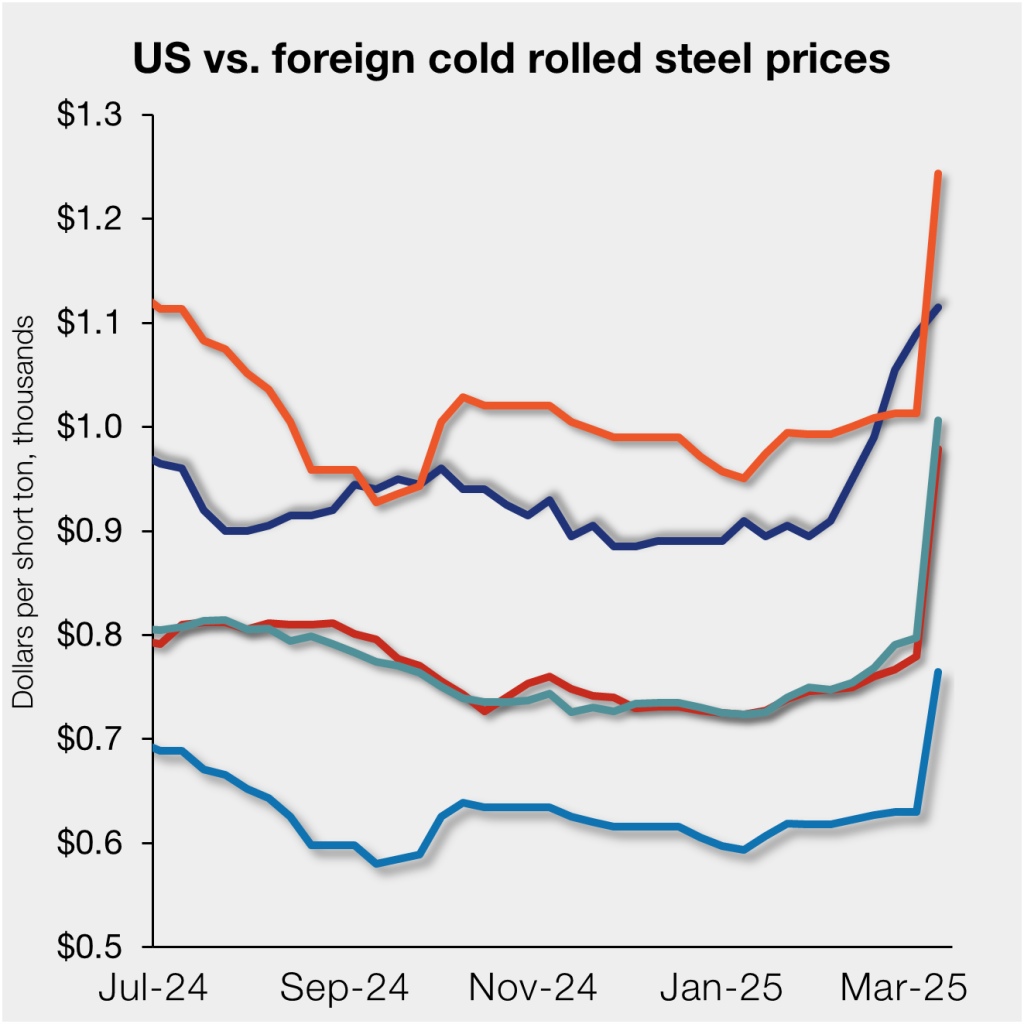
    US cold-rolled (CR) coil prices saw another increase this week, a trend mirrored by offshore prices.

    But fully restored Section 232 tariffs on steel on March 12 cut the widening premium US prices had over most imports on a landed basis. A clear shift after the price spread between stateside-produced CR and imports had reached a 14-month high last week.

    David Schollaert

    Read more from David Schollaert

    Latest in Sheet

    Steel market chatter: Tight supply, strong demand keep sheet prices climbing

    In this week's Market Chatter, steel buyers point to tight supply and steady demand as reasons sheet prices could keep rising, with many expecting HRC to reach $1,400-1,449 per short ton in two months. Views on when the rally will peak are mixed, with some anticipating further increases while others mention softening demand and political uncertainty. Respondents also disagree on tariffs' impact. They say reshoring is generating activity but has yet to translate consistently into demand.

    ArcelorMittal Calvert electrical steel mill remains on track for 2027 start

    ArcelorMittal Calvert is progressing on the construction of its new $1.2-billion non-grain-oriented electrical steel (NGO or NOES) mill, with production slated to begin in 2027. The steelmaker reported in its third-quarter earnings that it's on track with the 150,000-metric-ton-per-year project, located adjacent to its existing sheet mill in Calvert, Ala. In a Nov. 11 stakeholder newsletter, ArcelorMittal said the electrical steel production lines are taking shape: an annealing and pickling line on the west side of the mill and an annealing and coating line on the east side.

    Imports fall back slightly in September, slide further in October

    Final import data for September from the US Commerce Department shows a slight decline from August’s 15-month high. And October’s license count suggests another month-on-month (m/m) decline in imports. September imports of 2,416,717 short tons (st) were down just 1% from 2,434,108 st in August, a 15-month high. October license data show a steeper 8% m/m fall to 2,214,730 st (Figure 1, left). August appears to have been the peak for the recovery in imports, which has been ongoing since February of this year, when we saw some of the lowest levels since 2020.

    Steel exports fall in September to lowest rate of the year

    US steel exports eased 3% from August to September, marking the third consecutive monthly decline following June’s 17-month high, according to recently released US Department of Commerce figures. Exports have been historically low since early 2025 and remain weak compared to volumes seen in prior years. In September, 615,000 short tons (st) of steel were shipped outside of the country, 2% below the average monthly export rate of the past twelve months. September trade was 3% higher than the same month of 2025, 19% lower than September 2024, 21% lower than September 2023, and 15% lower than September 2022. For context, exports fell to a five-year low of 469,000 st in December and reached a near-five-year high of 914,000 st in May 2023.

    Nucor ups spot HR coil to $1,295/ton

    Nucor said on Monday, Nov. 9, that its consumer spot price (CSP) for hot-rolled (HR) coil will be $1,295 per short ton (st) this week, up $15/st from the prior week. The CSP for HR coil from California Steel Industries (CSI) on the West Coast will be $1,365/st, also up $15/st from last week. Nucor continues to offer lead times of three to five weeks, according to its letter to customers. You can track mill price announcements on our website. Steel Market Update (SMU) published a weekly price assessment on Tuesday, Nov. 3, showing HR coil prices averaging $1,350/st, up $45/st from the previous week. We will update our prices on the evening of Tuesday, Oct. 10.