• Skip to main content

    Contributor: David Schollaert

    David Schollaert

    Read more from David Schollaert
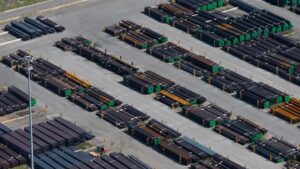
    pipe yard

    US rigs reach multi-year high, Canadian activity edges lower

    The latest count of active drilling rigs in the US rose, while activity eased in Canada this week, according to oil and gas rig count data published by Baker Hughes. The US rig count moved up to 607 rigs this week, reaching a 30-month high. Compared with this time last year, 53 more rigs are in operation today. Canada’s count slipped by two to 231 rigs this week, starting a bit of a seesaw pattern over the past five weeks. Activity is up from the same week of 2025, with 36 more rigs operating today.
    North American auto output rebounds in October

    North American auto assemblies rebounded 6.5% from September to 1.369 million units in October, driven by improved personal and commercial vehicle production, according to GlobalData. After steady gains through Q2, automotive production has been inconsistent, continuing a seesaw pattern, evident again last month. Still, assemblies remain muted and well below pre-pandemic levels. Total production was nearly even with October 2025, down 0.5% from a year earlier. Still, last month’s production total was 6.3% above 2026’s monthly average of 1.287 million units.

    AIA: Architecture billings remain weak in October

    Architecture firms continued to report declining billings in October, though commercial/industrial practices remained a brighter spot, according to the latest Architecture Billings Index (ABI) release from the American Institute of Architects (AIA) and Deltek. The October ABI stood at 44.9 (Figure 1), little changed from September’s 44.7, and indicating continued weakness in architecture business conditions. New project inquires increased again, but the pace of growth slowed from September. Meanwhile, the value of newly signed design contracts continued to decline, suggesting client interest has yet to translate into a sustained improvement in committed work.

    Demand index climbs, remains near 5-year high

    SMU’s Steel Demand Index rose two points to 66.5 in mid-November from 64.5 in mid-October. While it remains below a five-year high reached in mid-September, it is up 28 points from a reading of 38.5 a year ago. The result signals broadly improving flat-rolled steel demand, while buyer feedback points to strength in sectors such as data centers and border-wall construction. The index has been in expansion territory since late November 2025. Highly extended lead times, limited spot availability, mill outages, and historically reduced import competition continue to support domestic prices and apparent demand across the supply chain.

    Nucor Plate Group keeps fuel surcharge unchanged for December

    Nucor Plate Group will maintain its previously announced fuel surcharge of $40 per short ton (st) for next month, effective for all shipments beginning Dec. 1. The move comes after the Charlotte, N.C.-based steelmaker most recently doubled its surcharge to $40/st with its Oct. 15 notice. Recall that Nucor first said in April that the fuel surcharge was necessary to address rising costs, initially setting the surcharge at $10/st on April 16.

    SMU Price Ranges continue upward with spot tons still extremely scarce

    Sheet and plate prices continued to march higher on limited availability and no signs of a typical year-end slowdown. Prices have been rising since September 2025, the longest price rally in SMU’s data history – surpassing even the 2020-2021 rally. Buyers said they saw few signs of the rally stopping anytime soon amid late mill deliveries, scarce spot tons, limited contract tons, and strong demand. Availability continues to trump price, buyer sources said. To secure tons from mills, some sources continue to report buying from overseas – even as import lead times stretch into Q2. Others said they were concerned about taking positions that far out and so are buying from depot stocks held by traders – even if it means paying a significant premium.

    Mill Orders log fresh high, as on-order volumes swell

    SMU’s Mill Order Index (MOI) increased further in October, up for a sixth straight month and setting a new top mark. The increase came as service center on-order volumes and new mill order entries extended their record highs, including the post-pandemic snapback in demand, according to SMU’s latest service center inventory data. Results suggest inventories remain uncomfortably lean as service centers try to restock in a market where spot tons are scarce, and contract tons are significantly delayed.

    AISI: Southern rebound lifts US steel production, again

    US raw steel production continues its broad seesaw pattern, bouncing back from the prior week’s decline, according to the latest American Iron and Steel Institute (AISI) figures. Raw steel output has fluctuated sharply since late summer, reaching an 18-year high at the end of October before returning to more typical levels the following week. Despite the wide ebb and flows of late, production has generally trended lower since seeing sustained growth through May, though it remains historically strong compared to recent years.

    Alacero Summit rundown: China pressure sharpens calls for steel protection, regional cooperation

    Mexico and Latin America need a stronger response to subsidized steel and manufacturing overcapacity, according to speakers at Alacero Summit 2026. “What we cannot do is compete against a state,” said Máximo Vedoya, Ternium CEO, in his opening remarks. Vedoya maintained that Latin American (Latam) steelmakers can compete in the international landscape under fair conditions, but state-backed competition requires a stronger policy response.

    steel coils

    October service center shipments and inventories report

    US service centers’ flat-rolled steel supply increased marginally for a second straight month in October. Shipping days of supply rose to 46.6 last month, according to SMU data. That figure marks a 1.7% increase from 45.9 shipping days in September. October’s result represents continued modest gains after inventories hit a five-year low in August. Despite the uptick, inventories are nearly 13% below October 2025 levels. Sheet inventories have averaged ~48 shipping days of supply year-to-date, down nearly 17% over the same year-ago period. Flat-rolled inventories represented 2.12 months of supply in October, down 3.0% from 2.18 in September, and 8.6% below October 2025’s 2.32 months. The month-on-month (m/m) decline in months of supply resulted from a decline (-9.6%) in intake that was backed by a modest 4.1% m/m increase in shipments.

    Nucor again raises spot HR coil by $15/ton

    Nucor said on Monday, Nov. 16, that its consumer spot price (CSP) for hot-rolled (HR) coil will be $1,310 per short ton (st) this week, up $15/st from last week. The CSP for HR coil from California Steel Industries (CSI) on the West Coast will be $1,380/st, also up $15/st from last week. Nucor continues to offer lead times of three to five weeks, according to a letter to customers. Nucor has held or increased its weekly hot band CSP since Aug. 25, 2025. The steelmaker's CSP is up $435/st over the 64-week run.

    Nucor aims to raise plate prices by $70/ton, opens December orderbook

    Nucor said on Friday morning it plans to increase plate prices by $70 per short ton (st) as it opens its December order book. The Charlotte, N.C.-based steelmaker said in a letter to customers that orders must be submitted by Nov. 27 to be considered. You can check out SMU’s Steel Mill Price Announcement Calendar to follow announced pricing moves. SMU’s price assessment for plate currently stands at $1,550/st on average, as of Tuesday, Nov. 10, up $55/st vs. the prior week.

    Lead times extend deeper into 2027, some see no availability until late Feb

    Lead times for sheet and plate products continue to extend in a US steel market still in the grip of a historic supply squeeze, according to the latest SMU steel market survey data. Average lead times now extend into late January 2027, with some mills not quoting availability until mid/late February. Lead times for all sheet products except Galvalume stand at their highest point since the post-Covid demand snapback in 2021. And plate lead times have exceeded their 2021 peak, repeatedly setting new record highs in our data series over the past month. (We started collecting plate lead time data in 2018. Our sheet lead time figures go back to 2012.)

    SMU flat-rolled market survey results now available

    The results of the latest Steel Market Update (SMU) flat-rolled market survey are now available on our website to all premium members. After logging in, look under the Data tab for Market Reports, and there you will find the Flat-Rolled Survey Results section. Previous survey results are also available on that page. If you need help accessing these results, or if your company would like to have your voice heard in our future surveys, contact smu@crugroup.com.

    Nucor ups spot HR coil to $1,295/ton

    Nucor said on Monday, Nov. 9, that its consumer spot price (CSP) for hot-rolled (HR) coil will be $1,295 per short ton (st) this week, up $15/st from the prior week. The CSP for HR coil from California Steel Industries (CSI) on the West Coast will be $1,365/st, also up $15/st from last week. Nucor continues to offer lead times of three to five weeks, according to its letter to customers. You can track mill price announcements on our website. Steel Market Update (SMU) published a weekly price assessment on Tuesday, Nov. 3, showing HR coil prices averaging $1,350/st, up $45/st from the previous week. We will update our prices on the evening of Tuesday, Oct. 10.

    Nucor temporarily halted secondary offers, rattling a tight US market

    Nucor opened its secondary and excess product bid list across all its flat-rolled mills last Monday, as it typically does, market participants told SMU. But by Wednesday, when bidding was scheduled to close, Nucor notified buyers it would not be awarding any bids that week. The abrupt close sent a shock through the secondary market, they said. “There will be no awards this week,” emails from Nucor sales representatives to customers confirmed. “Effective immediately, we are placing a temporary hold on all secondary sales.”

    SMU scrap market survey results now available

    SMU’s November ferrous scrap market survey results are now available on our website to all premium members. After logging in at steelmarketupdate.com, visit the Pricing and Analysis tab and look under the “survey results” section for Ferrous Scrap Survey results. Past scrap survey results are also available under that selection. If you need help accessing the survey results or if your company would like to have your voice heard in our future surveys, contact smu@crugroup.com.

    Drilling activity ticks up in the US, eases in Canada

    The latest tally of active drilling rigs moved marginally higher in the US, up for the first time in five weeks. Activity eased in Canada this week, according to oil and gas rig count data published by Baker Hughes. The US rig count increased to 604 rigs this week, setting an 18-month high watermark. Compared with this time last year, 56 more rigs are in operation today. Canada’s count declined by three to 223 rigs this week, easing for the first time in three weeks. Activity is up from the same week of 2025, with 32 more rigs operating today.
    Market chatter: Supply, not price, dominates steel buyers’ concerns

    On Monday and Tuesday of this week, SMU polled steel buyers on an array of topics, ranging from market prices, demand, and inventories to tariffs, imports, and evolving market events. We are sharing a selection of the comments we received below, in each buyer’s own words. Before diving in, we reviewed all the responses collected and compiled these key takeaways: Respondents overwhelmingly anticipate further increases. Buyers cite limited supply, mill delays, low inventories, and steady-to-strong demand. Most say demand is generally stable to improving, with some purchasing driven by fears of higher prices or unavailable material rather than stronger underlying consumption. Most respondents report faster inventory turnover, while shortages are constraining sales and, in some cases, prompting customer allocations. Buyers increasingly see imports as a way to secure scarce material, though domestic-origin requirements, delivery timing, and pricing risks remain obstacles.

    Sheet prices surge as '26 market squeeze spills into '27

    Sheet prices soared this week as market participants increasingly predict that the strong market characterizing 2026 will stretch well into 2027. And with extremely limited spot availability, mills that have spot tons to sell are charging a significant premium, they said. The result: Sheet prices saw their highest week-over-week gains since March 2025, according to SMU's pricing records. That's when President Trump shocked the market by expanding Section 232 tariffs to cover traditional US allies such as Canada, Mexico, and the EU.

    Deacero casts first billet at new Ramos Arizpe mini-mill

    Mexican longs producer Deacero has cast the first billet at its new minimill in Ramos Arizpe, Mexico, moving the Danieli-supplied caster into commissioning. It's a key milestone for Deacero's $600-million Ramos II mini-mill, said Italian plant engineering and equipment provider. "The achievement further strengthens the long-standing collaboration between Deacero and Danieli, and further confirms Danieli’s already-established presence in the Mexican long-products market," the company said in a statement on Nov. 2.

    US steel output reaches 18-year high as South leads gains: AISI

    Domestic raw steel production surged last week, reaching its highest output in almost two decades, according to the latest American Iron and Steel Institute (AISI) figures. While the seesaw pattern continued for US production this past week, production swelled to its highest reading since Aug. 23, 2008, driven by a massive swing in the South. The increase reversed the recent downward trend, with a sharp rebound in the South accounting for nearly all the weekly gain. Production has fluctuated considerably over the past two months, reaching both an 18-year high and its lowest level since January.

    Nucor increases spot HR to $1,280/ton

    Nucor said on Monday, Nov. 2, that its consumer spot price (CSP) for hot-rolled (HR) coil will be $1,280 per short ton (st) this week, up $10/st from last week. The CSP for HR coil from California Steel Industries (CSI) on the West Coast will be $1,350/st, also up $10/st from a week earlier. Nucor continues to offer lead times of three to five weeks, according to its letter to customers. You can track mill price announcements on our website. Steel Market Update published a weekly price assessment on Tuesday, Oct. 27, showing HR coil prices averaging $1,305/st, up $15/st from the previous week.

    Drilling activity holds in the US, moves higher in Canada

    The latest tally of active drilling rigs held steady in the US for a fourth straight week, while activity rose further in Canada this week, according to oil and gas rig count data published by Baker Hughes. The US rig count remained unchanged at 603 rigs this week, maintaining a 17-month high. Compared with this time last year, 57 more rigs are in operation today. Canada’s count rose by six to 226 rigs this week, gaining ground for a second consecutive week. Activity is up from the same week of 2025, with 39 more rigs operating today.
    Final Thoughts: Longer waits, higher stakes

    We’re in rarefied air for the US domestic steel industry. Mill lead times are approaching or even exceeding (in the case of plate) records set in 2021. Prices, meanwhile, are on an epic run—13 months and counting. Availability, not price, is the largest hurdle buyers are facing. And market participants think the shortage could stay around for a while. Incoming imports and mills catching up after fall maintenance could ease the squeeze. Even so, most sources do not expect meaningful relief until 2027.

    SMU flat-rolled market survey results now available

    The results of the latest Steel Market Update (SMU) flat-rolled market survey are now available on our website to all premium members. After logging in, look under the Data tab for Market Reports, and there you will find the Flat-Rolled Survey Results section. Previous survey results are also available on that page. If you need help accessing these results, or if your company would like to have your voice heard in our future surveys, contact smu@crugroup.com.

    Mill lead times climb to new highs, buyers expect little relief

    Lead times for sheet and plate products continued to lengthen amid historically tight supply, according to the latest SMU steel market survey data. Average lead times now extend into January 2027, with some mills quoting availability well into February. Lead times for all sheet products except Galvalume stand at their highest point since the post-Covid demand snapback in 2021. Plate lead times exceed their 2021 peak, setting a record in our data series, which dates to 2018. (We started collecting sheet lead times earlier, in 2011.)

    Fall maintenance winding down, but key outages remain

    The busy fall maintenance season isn’t over yet. Mill outages have rolled along since September, squeezing an already tight sheet market heading into November and beyond. Another round of scheduled maintenance is approaching, with outages still ahead at North Star BlueScope, ArcelorMittal Calvert, and Nucor Berkeley. Much of the fall maintenance calendar is now in the rearview mirror. September and October outages included U.S. Steel’s Gary Works; Nucor’s Hickman, Decatur, Gallatin and Crawfordsville operations; Steel Dynamics’ Sinton and Columbus mills; Cleveland-Cliffs’ Dearborn hot strip mill; NLMK Portage; and Big River Steel Works.