• Skip to main content

    Sheet

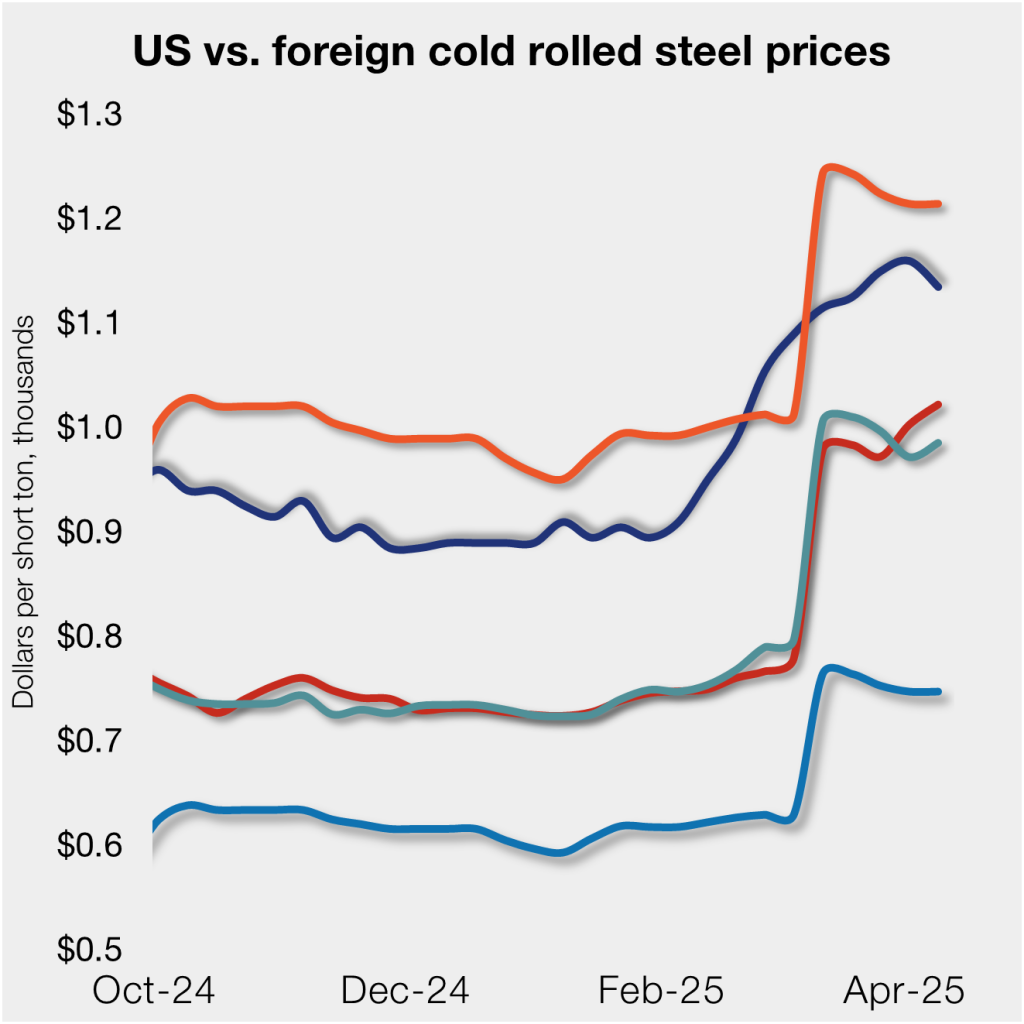
    US, offshore CRC prices diverge

    Written by David Schollaert


    US cold-rolled (CR) coil prices declined this week, slipping for the first time since early February. Most offshore markets deviated, moving higher this week.

    As a result, the US premium over imports on a landed basis widened. The move was helped by a tighter gap since the re-emergence of Section 232 on March 12.

    David Schollaert

    Read more from David Schollaert

    Latest in Sheet

    Cliffs shifts customers to index-linked, take-or-pay contracts

    Cleveland-Cliffs Inc. expects to earn more from the repricing of contract tonnage than it previously projected. The Cleveland-based steelmaker raised its estimate for the earnings benefit of the repricing to about $850 million from about $500 million. The company also said negotiations for 2027 contracts are progressing better than expected. More than half of the 2027 renewal process was complete as of Cliffs' third-quarter earnings call on Monday morning.

    Cleveland-Cliffs postpones Burns Harbor furnace reline to 2028

    Cleveland-Cliffs Inc. has rescheduled the planned reline of the C blast furnace at its Burns Harbor steel mill in northwest Indiana from mid-2027 to April 2028, company executives said. The delay allows the Cleveland-based steelmaker to keep the furnace, which has annual capacity of ~2.2 million short tons, operating while steel prices and demand remain favorable for mills, they said during the company’s third-quarter earnings call on Monday.

    supply

    September service center shipments and inventories report

    US service centers’ flat-rolled steel supply increased marginally in September, gaining ground for only the second time all year. Shipping days of supply rose to 45.9 last month, according to SMU data. That figure marks a 3.7% increase from August. September’s result represents a modest gain after inventories hit a five-year low the previous month. But it’s nearly 16% below September 2025 levels. Sheet inventories have averaged ~45 shipping days of supply over the past six months. Flat-rolled inventories represented 2.18 months of supply in September, up 3.7% from August. However, the figure was 15.5% below September 2025. The month-on-month (m/m) gain in inventories resulted from a boost (+21.2%) in intake that was partially offset by a 5% increase in shipments.