CR imports more attractive as US prices remain on the rise
Cold-rolled (CR) coil prices ticked up in the US this week, as offshore prices mostly trended lower.


Cold-rolled (CR) coil prices ticked up in the US this week, as offshore prices mostly trended lower.
South Korea has overtaken Canada as the top foreign supplier of steel to the US market.
For the next month, CRU forecasts that iron ore demand will fall m/m while metallurgical coal to be stable.
The US HRC futures curve has continued to move higher, particularly in the deferred months, suggesting the market is pricing a slower return to balance.
Earlier this week, SMU polled steel buyers on an array of topics, ranging from prices, demand, and inventories to tariffs, imports, and evolving market conditions.
Manufacturing activity in New York state increased modestly in June, easing after posting strong growth the month prior, according to the Empire State Manufacturing Survey.
Drilling activity ticked higher this week in both the US and Canada, according to recently released rig count figures from Baker Hughes.
SMU’s average price for domestic HR was $1,130 per short ton (st) this week, $15/st higher week over week (w/w). In offshore markets last week, prices were largely down, following a trend seen since late April.
SMU’s Steel Demand Index ticked back up from late May, remaining in elevated territory, according to mid-June indicators.
May was the fifth consecutive month of expansion for the US manufacturing sector, according to the most recent Institute for Supply Management (ISM) report.
Canada’s steel production dropped sharply in May, falling 15% year over year and running 14% lower year-to-date, according to Earth-i’s Savant Global Monitoring Index. May’s production was just under 900,000 metric tons.
SMU’s Mill Order Index recovered in May, reclaiming some momentum lost the month prior.
SMU’s sheet price indices increased further this week, while plate held steady, all at multi-year highs.
Apparent steel supply eased from March to April on reduced mill shipments per recent Department of Commerce and American Iron and Steel Institute (AISI) data.
US steel exports improved 2% from March to April to the highest monthly volume seen in 13 months. Although up, trade remains historically low
SMU and AMU are pleased to announce that Wells Fargo Managing Director Timna Tanners will be joining us for a Community Chat webinar on Wednesday, June 24, at 11 am ET.
The volume of raw steel produced by US mills slipped to a seven-week low last week but remains historically high, according to American Iron and Steel Institute (AISI) figures released on Monday.
Total heating and cooling equipment shipments declined 5% in April, according to AHRI figures.
US service centers’ flat-rolled steel supply declined for a fourth straight month in May, with shipping days of supply slipping to 44.7 on an adjusted basis, according to SMU data.
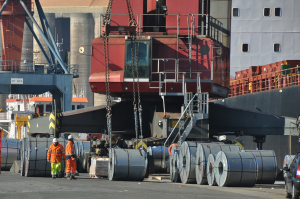
After reaching historic lows late last year, import volumes have increased each month of 2026, according to recently released US Commerce Department data.
Oil and gas drilling activity in Canada picked up over the past week, while drilling in the US remained mostly steady.
SMU’s latest steel buyers market survey results are now available on our website to all premium members.
SMU’s Steel Buyers’ Sentiment Indices remained strongly optimistic this week and continue to indicate that buyers are confident in their companies’ prospects.
A major trade case finalized late last year, along with higher Section 232 tariffs, account for the reduced imports.
Steel mill lead times extended this week on both sheet and plate products, now at multi-year highs.
This week we saw continued low negotiation rates across all products, with cold rolled and plate the least negotiable and galvanized the most.
The price gap between US hot-rolled coil (HR) and landed offshore product continues to narrow, as stateside prices are now, on average, carrying a premium over imports. Domestic tags are still outpacing imported hot band as pricing dynamics diverge.
All five of SMU’s price indices increased this week to new multi-year highs. Prices have increased by 20-25% since the beginning of the year.
The American Iron and Steel Institute (AISI) reports that US steel shipments fell from March to April.
Domestic steel mill output remained historically strong last week, holding within earshot of a multi-year high.