CR imports more attractive as US prices remain on the rise
Cold-rolled (CR) coil prices ticked up in the US this week, as offshore prices mostly trended lower.
Cold-rolled (CR) coil prices ticked up in the US this week, as offshore prices mostly trended lower.
SMU’s average price for domestic HR was $1,130 per short ton (st) this week, $15/st higher week over week (w/w). In offshore markets last week, prices were largely down, following a trend seen since late April.
The volume of raw steel produced by US mills slipped to a seven-week low last week but remains historically high, according to American Iron and Steel Institute (AISI) figures released on Monday.
The price gap between US hot-rolled coil (HR) and landed offshore product continues to narrow, as stateside prices are now, on average, carrying a premium over imports. Domestic tags are still outpacing imported hot band as pricing dynamics diverge.
The American Iron and Steel Institute (AISI) reports that US steel shipments fell from March to April.
Domestic steel mill output remained historically strong last week, holding within earshot of a multi-year high.
The price gap between US hot-rolled coil (HR) and landed offshore product continues to narrow toward parity.
Domestic raw steel output remains within reach of a multi-year high, per AISI figures.
Domestic raw steel production ticked up to the highest weekly output rate recorded since March 2020, according to recently published American Iron and Steel Institute (AISI) data.
The Trump administration's invocation of the Defense Production Act authorizes the Department of Energy to use DPA tools to accelerate construction, expand domestic manufacturing capacity, and shore up critical supply chains – all areas with direct implications for steel.
Domestic raw steel production increased to a new multi-year high last week, per AISI figures.
The price gap between US hot-rolled coil (HR) and landed offshore product tightened this week. The dynamic continues even as stateside and import prices diverged a bit vs. the prior week.
The volume of raw steel produced by US mills eased last week but remains within earshot of the multi-year high set one week prior
The price gap between US hot-rolled coil (HR) and landed offshore product tightened this week. The dynamic continues as both stateside and offshore prices have largely trended higher.
Domestic mill production ticked up to a new multi-year high last week, according to recently published American Iron and Steel Institute (AISI) figures.
Raw steel production increased for the fourth-consecutive week last week to a new multi-year high, according to the American Iron and Steel Institute (AISI).
The American Iron and Steel Institute (AISI) reported a 2.5% decrease in domestic steel shipments for February compared to January. However, shipments are up 5.1% in 2026 from the same month in 2025.
The price gap between US hot-rolled coil (HR) and landed offshore product tightened this week.
Raw steel production recovered for the second-consecutive week and is now just 14,000 short tons below the four-year high production rate witnessed in mid-February.
CR imports from Germany, Italy, and Japan on a landed basis remain much more expensive than domestic product. But South Korean imports remain competitive, in theory, even with the 50% Section 232 tariff.
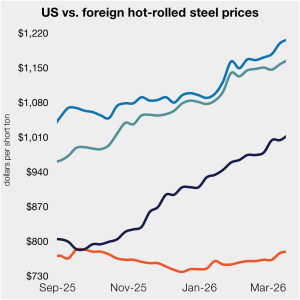
The price gap between US hot-rolled coil (HR) and landed offshore product remained within a tight band this week. The dynamic continues as both stateside and offshore prices have trended higher.
Domestic mill production was estimated at 1.78 million short tons last week, near the four-year high set one month ago.
Raw steel production declined last week for the third-consecutive week but remains historically strong, per AISI.
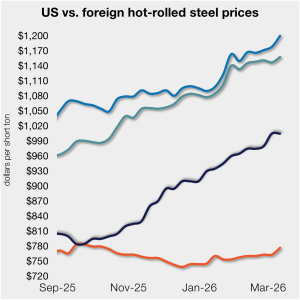
The price gap between US hot-rolled coil (HR) and landed offshore product widened this week, as stateside tags were little changed.
Raw production has trended upwards since the start of the year, reaching a four-year high in February.
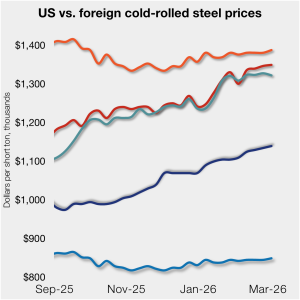
Cold-rolled (CR) coil prices ticked up in the US this week, matching a similar trend seen in most offshore markets as well.
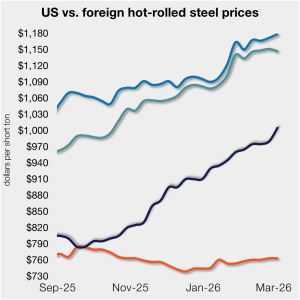
The price gap between US hot-rolled coil (HR) and landed offshore product tightened this week, as stateside tags continue to rise.
Domestic raw steel production has strengthened since the start of the year and reached a four-year high in mid-February.
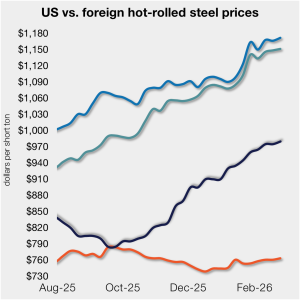
The price gap between US hot-rolled coil (HR/HRC) and landed offshore product remained largely flat again this week, as price movements stateside and abroad mirrored each other.
US hot-rolled coil prices are set to rise year on year in 2026, but the market will face heightened volatility as import flows recover and new domestic capacity comes online, CRU Research Principal Josh Spoores said at this year's Tampa Steel Conference.