• Skip to main content

    Plate

    Hot Rolled vs Plate Steel Prices: Plate Premium at 42%

    Written by Brett Linton


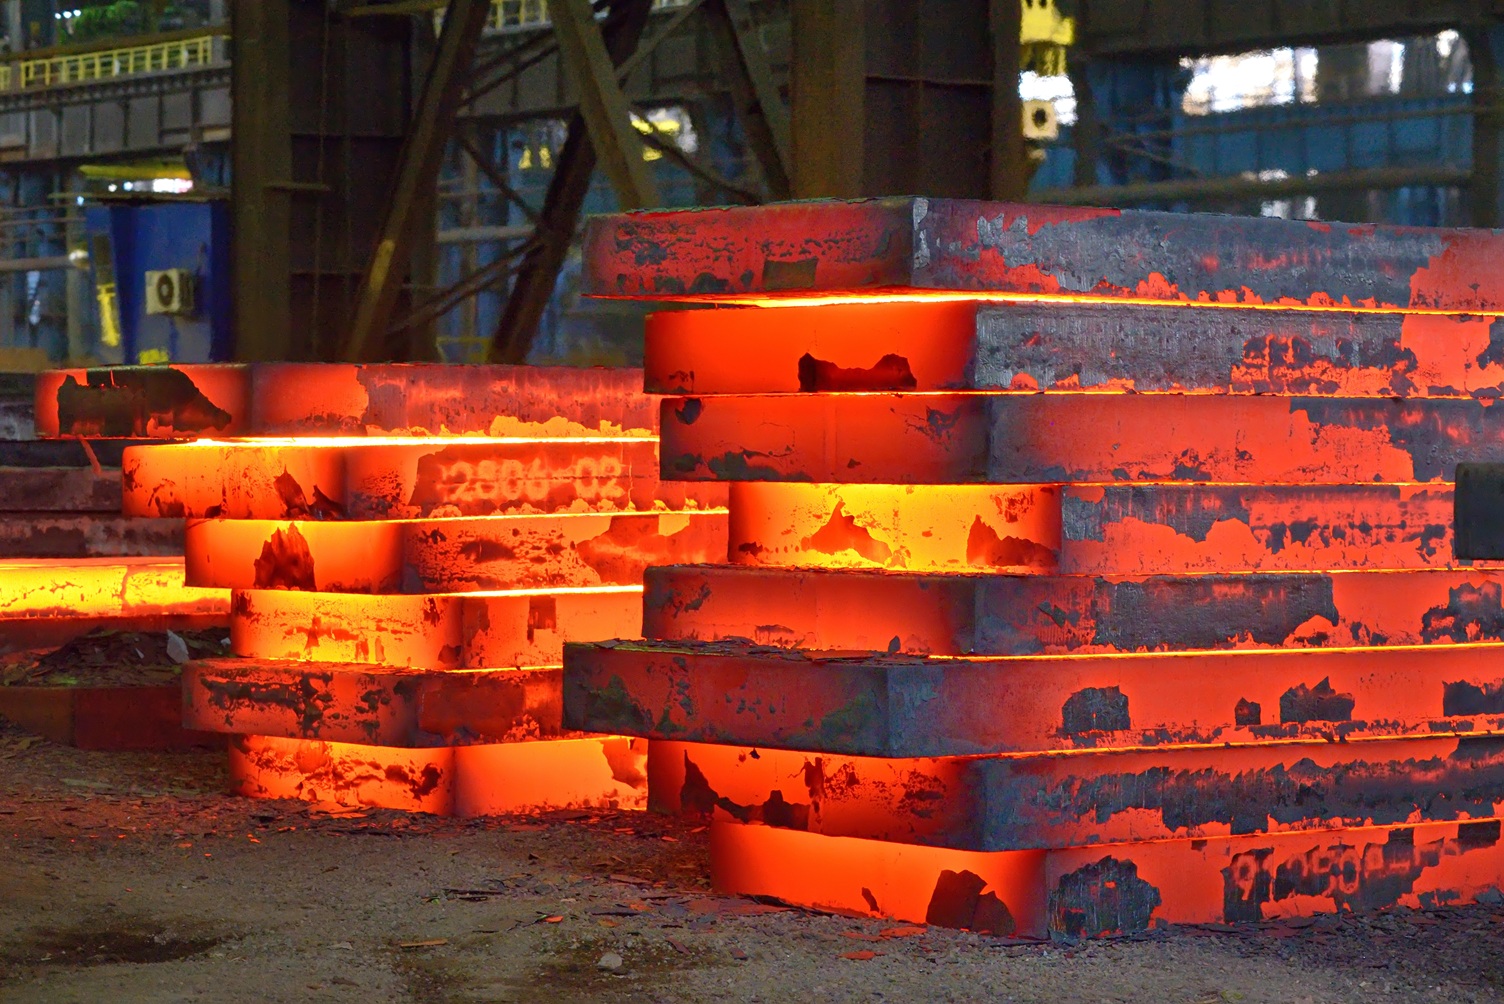
    Sheet steel prices are moving downwards after the March/April bump, while plate prices continue to hold their ground, according to SMU’s price indices published each Tuesday. Plate prices typically carry a premium over hot rolled prices because plate is a value-added product and requires more time on the mill.

    Hot rolled coil averaged $1,350 per ton ($67.50 per cwt) this week and has declined each of the past four weeks. Recall our index had reached a 14-month low of $1,000 per ton in the first week of March, following a record-high $1,955 per ton in September 2021. Our latest plate index averaged $1,925 per ton last week, down $15 per ton from the week prior but up $5 per ton from one month ago. Plate prices have been stable compared to sheet prices, with our plate index remaining between $1,775 and $1,940 for nearly 8 months now. 
    Brett Linton

    Read more from Brett Linton

    Latest in Plate

    Nucor aims to raise plate prices by $70/ton, opens December orderbook

    Nucor said on Friday morning it plans to increase plate prices by $70 per short ton (st) as it opens its December order book. The Charlotte, N.C.-based steelmaker said in a letter to customers that orders must be submitted by Nov. 27 to be considered. You can check out SMU’s Steel Mill Price Announcement Calendar to follow announced pricing moves. SMU’s price assessment for plate currently stands at $1,550/st on average, as of Tuesday, Nov. 10, up $55/st vs. the prior week.

    Lead times extend deeper into 2027, some see no availability until late Feb

    Lead times for sheet and plate products continue to extend in a US steel market still in the grip of a historic supply squeeze, according to the latest SMU steel market survey data. Average lead times now extend into late January 2027, with some mills not quoting availability until mid/late February. Lead times for all sheet products except Galvalume stand at their highest point since the post-Covid demand snapback in 2021. And plate lead times have exceeded their 2021 peak, repeatedly setting new record highs in our data series over the past month. (We started collecting plate lead time data in 2018. Our sheet lead time figures go back to 2012.)

    SMU flat-rolled market survey results now available

    The results of the latest Steel Market Update (SMU) flat-rolled market survey are now available on our website to all premium members. After logging in, look under the Data tab for Market Reports, and there you will find the Flat-Rolled Survey Results section. Previous survey results are also available on that page. If you need help accessing these results, or if your company would like to have your voice heard in our future surveys, contact smu@crugroup.com.

    SMU Survey: Steel mill negotiations remain rare as buyers face tight supply

    Only 5% of steel buyers surveyed by SMU this week said mills were willing to negotiate lower prices for new spot orders, suggesting mills retain substantial pricing leverage in a tight market. The share rose two percentage points from our previous survey two weeks ago but was nine points below the mid-October reading. This week's rate is just slightly higher than our previous survey when the negotiation rate fell to 3% — its lowest level since July 2021. Negotiation rates have trended downward all year as steel prices have continued to climb.

    JSW Steel USA completes $110M modernization at Texas mill

    JSW Steel USA has completed a $110-million modernization project at its plate mill in Baytown, Texas, a company spokesperson told SMU. “Baytown is back up,” the spokesperson said. “The planned outage is complete, and the mill is running across all of our existing processes.” “Our newly installed equipment is now in the hot commissioning and trialing phase, which is an exciting next step for the site,” she added.