Market Data
December 1, 2022
Consumer Confidence Down Again in November
Written by David Schollaert
US consumer confidence slipped again in November, declining for the second straight month amid ongoing high inflation and rising interest rates. Despite the weaker outlook, household spending has had a generally healthy start to winter holiday shopping, The Conference Board reported. The headline Consumer Confidence Index fell by two points in November to a reading of 102.2. The decrease comes after a decline of nearly six points the month prior. November’s figure is the lowest since July, according to the report. “Consumer confidence declined again in November, most likely prompted by the recent rise in gas prices,” said Lynn Franco, senior director of economic indicators at The Conference Board. “The Present Situation Index moderated further and continues to suggest the economy has lost momentum as the year winds down. Consumers’ expectations regarding the short-term outlook remained gloomy. Indeed, the Expectations Index is below a reading of 80, which suggests the likelihood of a recession remains elevated.” The data indicates Americans are taking a gloomier view of the economy. Before the pandemic, the index regularly topped 120. Inflation is near the worst in four decades, driving the cost of food, rent, clothing, and other essentials higher and chipping away at consumer confidence. “Inflation expectations increased to their highest level since July, with both gas and food prices as the main culprits,” Franco added. “Intentions to purchase homes, automobiles, and big-ticket appliances all cooled. The combination of inflation and interest rate hikes will continue to pose challenges to confidence and economic growth into early 2023.” The Present Situation Index, which measures consumer sentiment toward current business and labor market conditions, fell to 137.4 from 138.7 last month. The Expectations Index, which assesses the short-term outlook for income, business, and labor market conditions, slipped to 75.4 from 77.9. Calculated as a three-month moving average (3MMA) to smooth out volatility, The Conference Board’s Composite Index was 103.4, a 1.1-point increase versus October. The figure fell for the first time in four months and remains well behind a pre-pandemic high of 130.4 set in February 2020. The Composite Index is made up of two sub-indexes: consumers’ view of the present situation and their expectations for the future. Figure 1 below notes the 3MMA linear trend lines from January 2012 through November 2022 versus the trend lines of all three subcomponents of the index: Present Situation, Composite, and Future Expectations. All three were above the average composite line prior to the pandemic before falling consecutively through February 2021. The surge from March through June of 2021 pulled all three indexes above the composite line once again. But economic uncertainty continues to weigh on confidence and expectations. 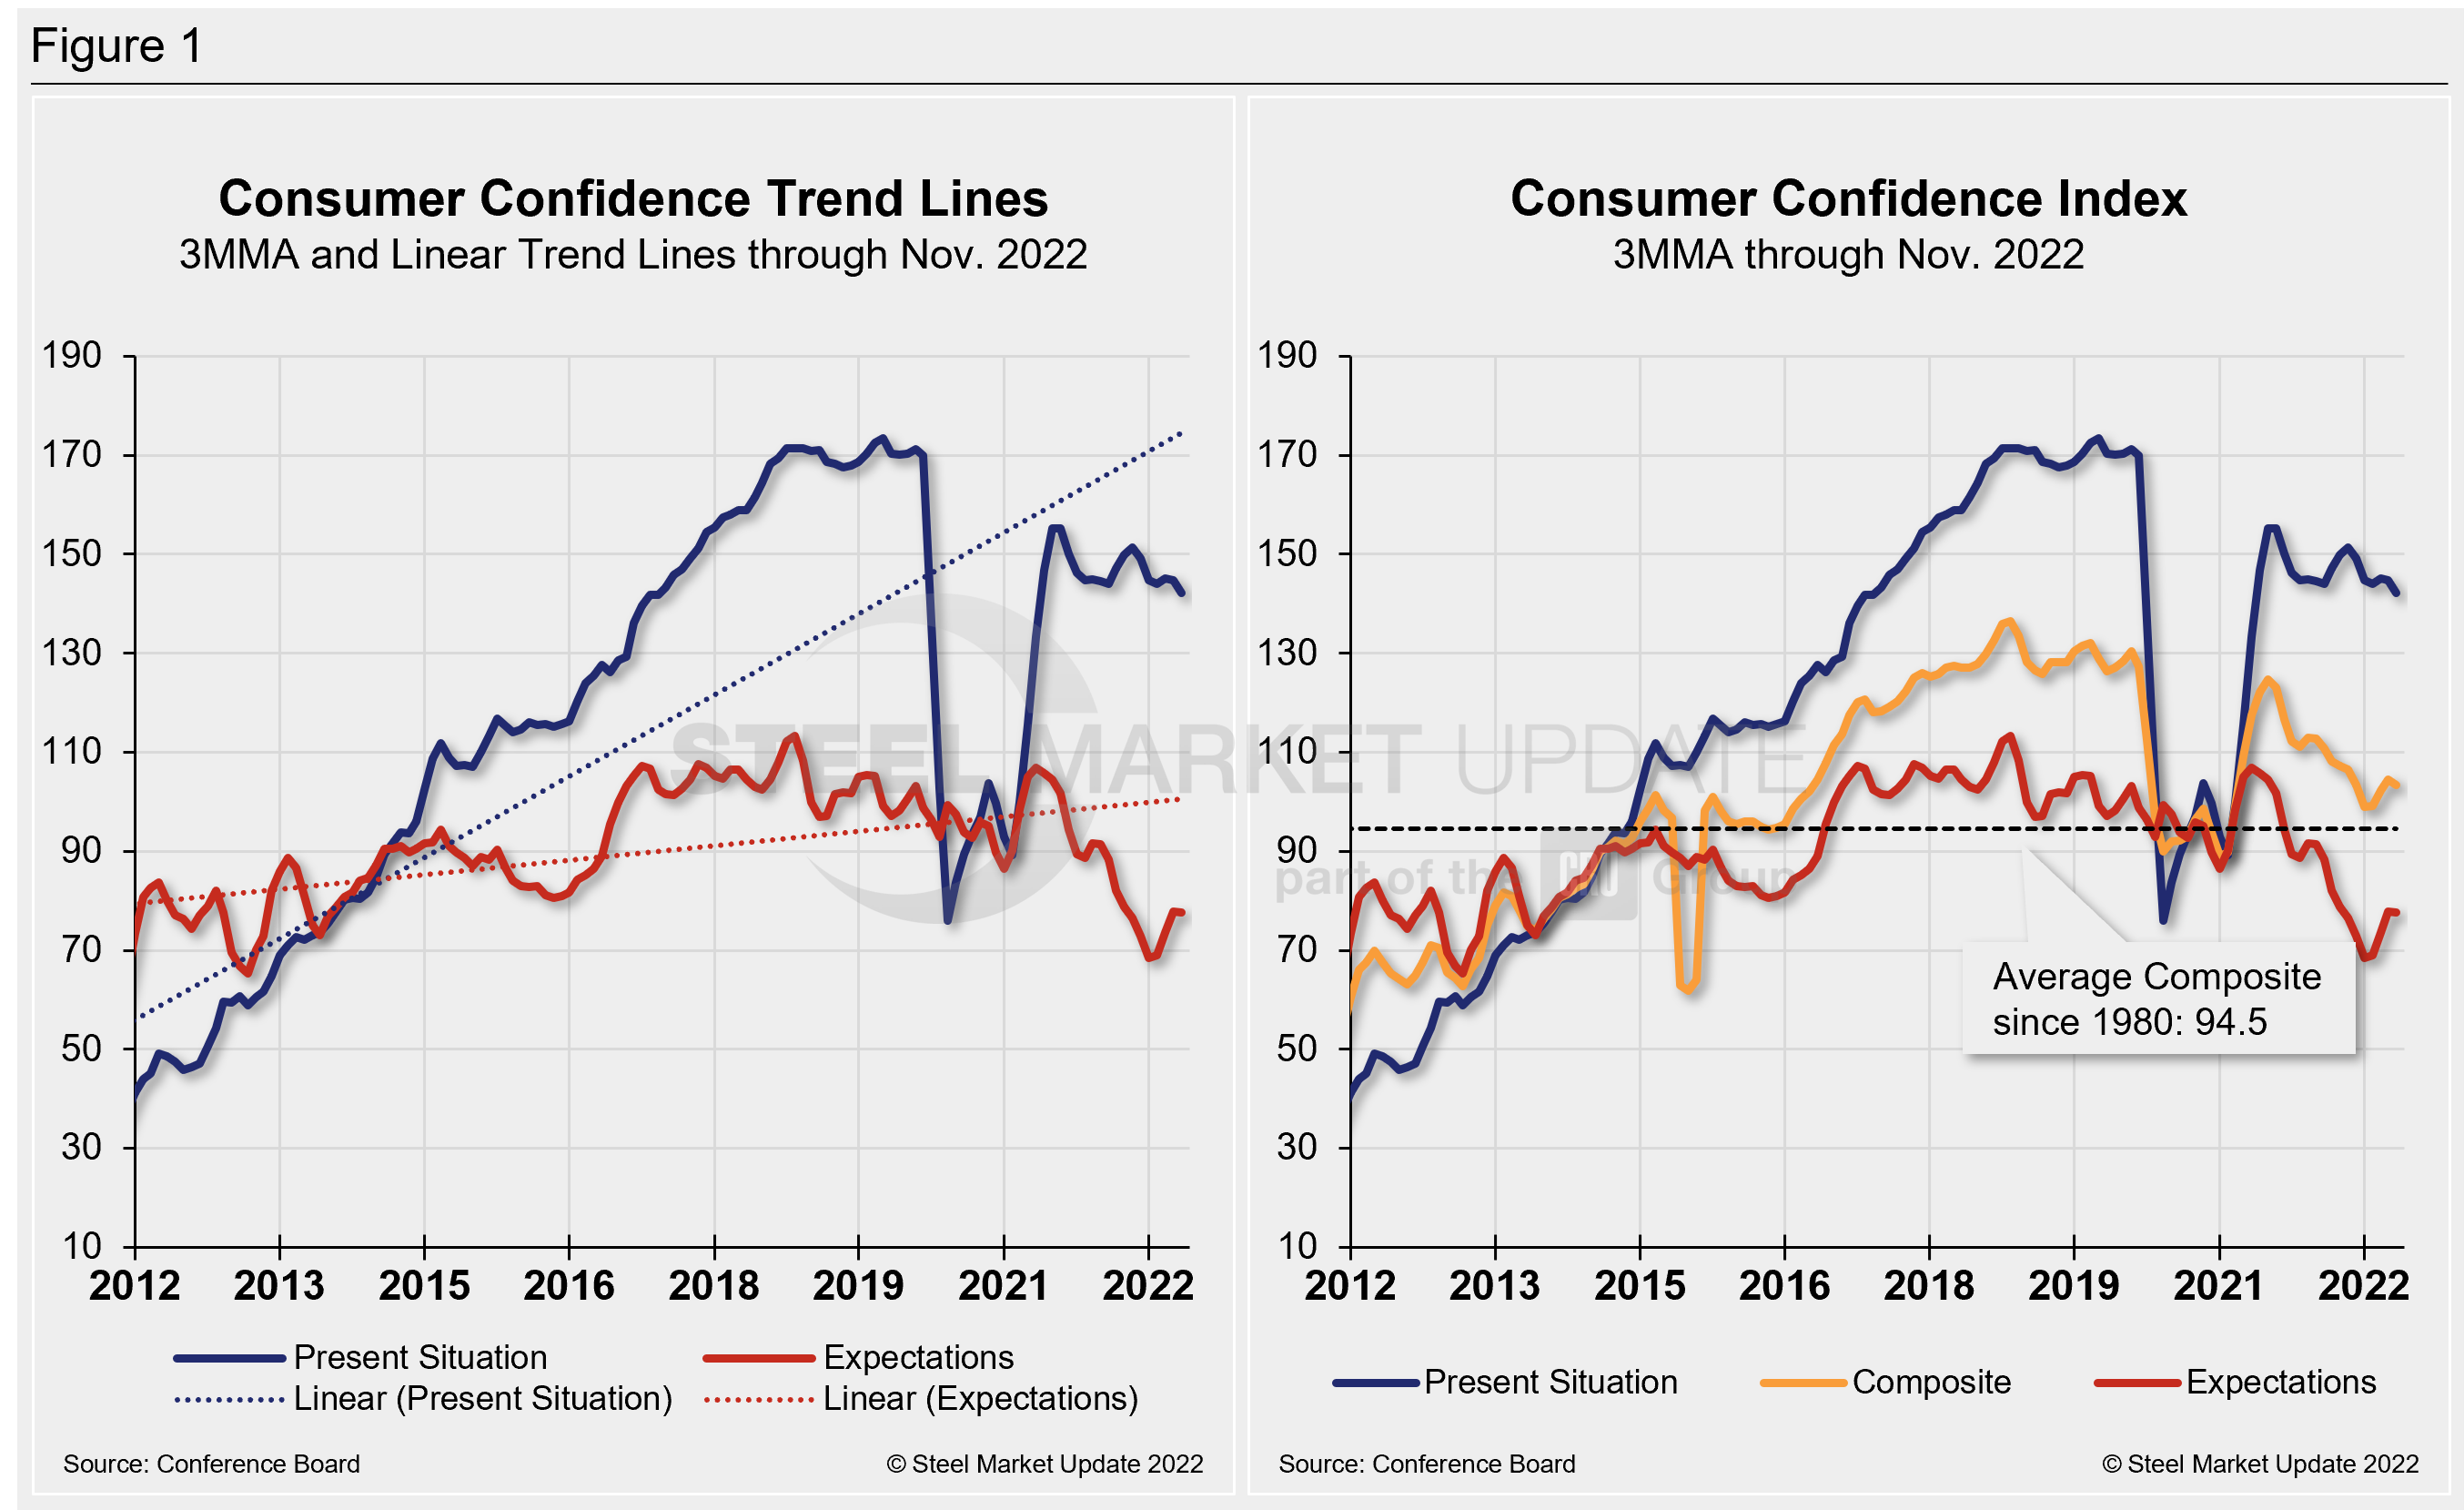 The table below compares November 2022 with November 2021 on a 3MMA basis. The headline index and its two sub-indexes have all been declining on a year-on-year (YoY) basis. Present Situation has seen a less aggressive fall, but they are all down notably, with Expectations showing the most volatility over the same period. All three are also showing declining momentum through November. When compared to the same 2019 pre-pandemic period, the Composite Index is down 23 points on a 3MMA basis. The Present Situation is down 28.1 points, while the Expectations reading is down 19.6 points this month when compared to the same period in 2019. The Consumer Confidence report includes employment data and purchase plans. These are summarized in the table below.
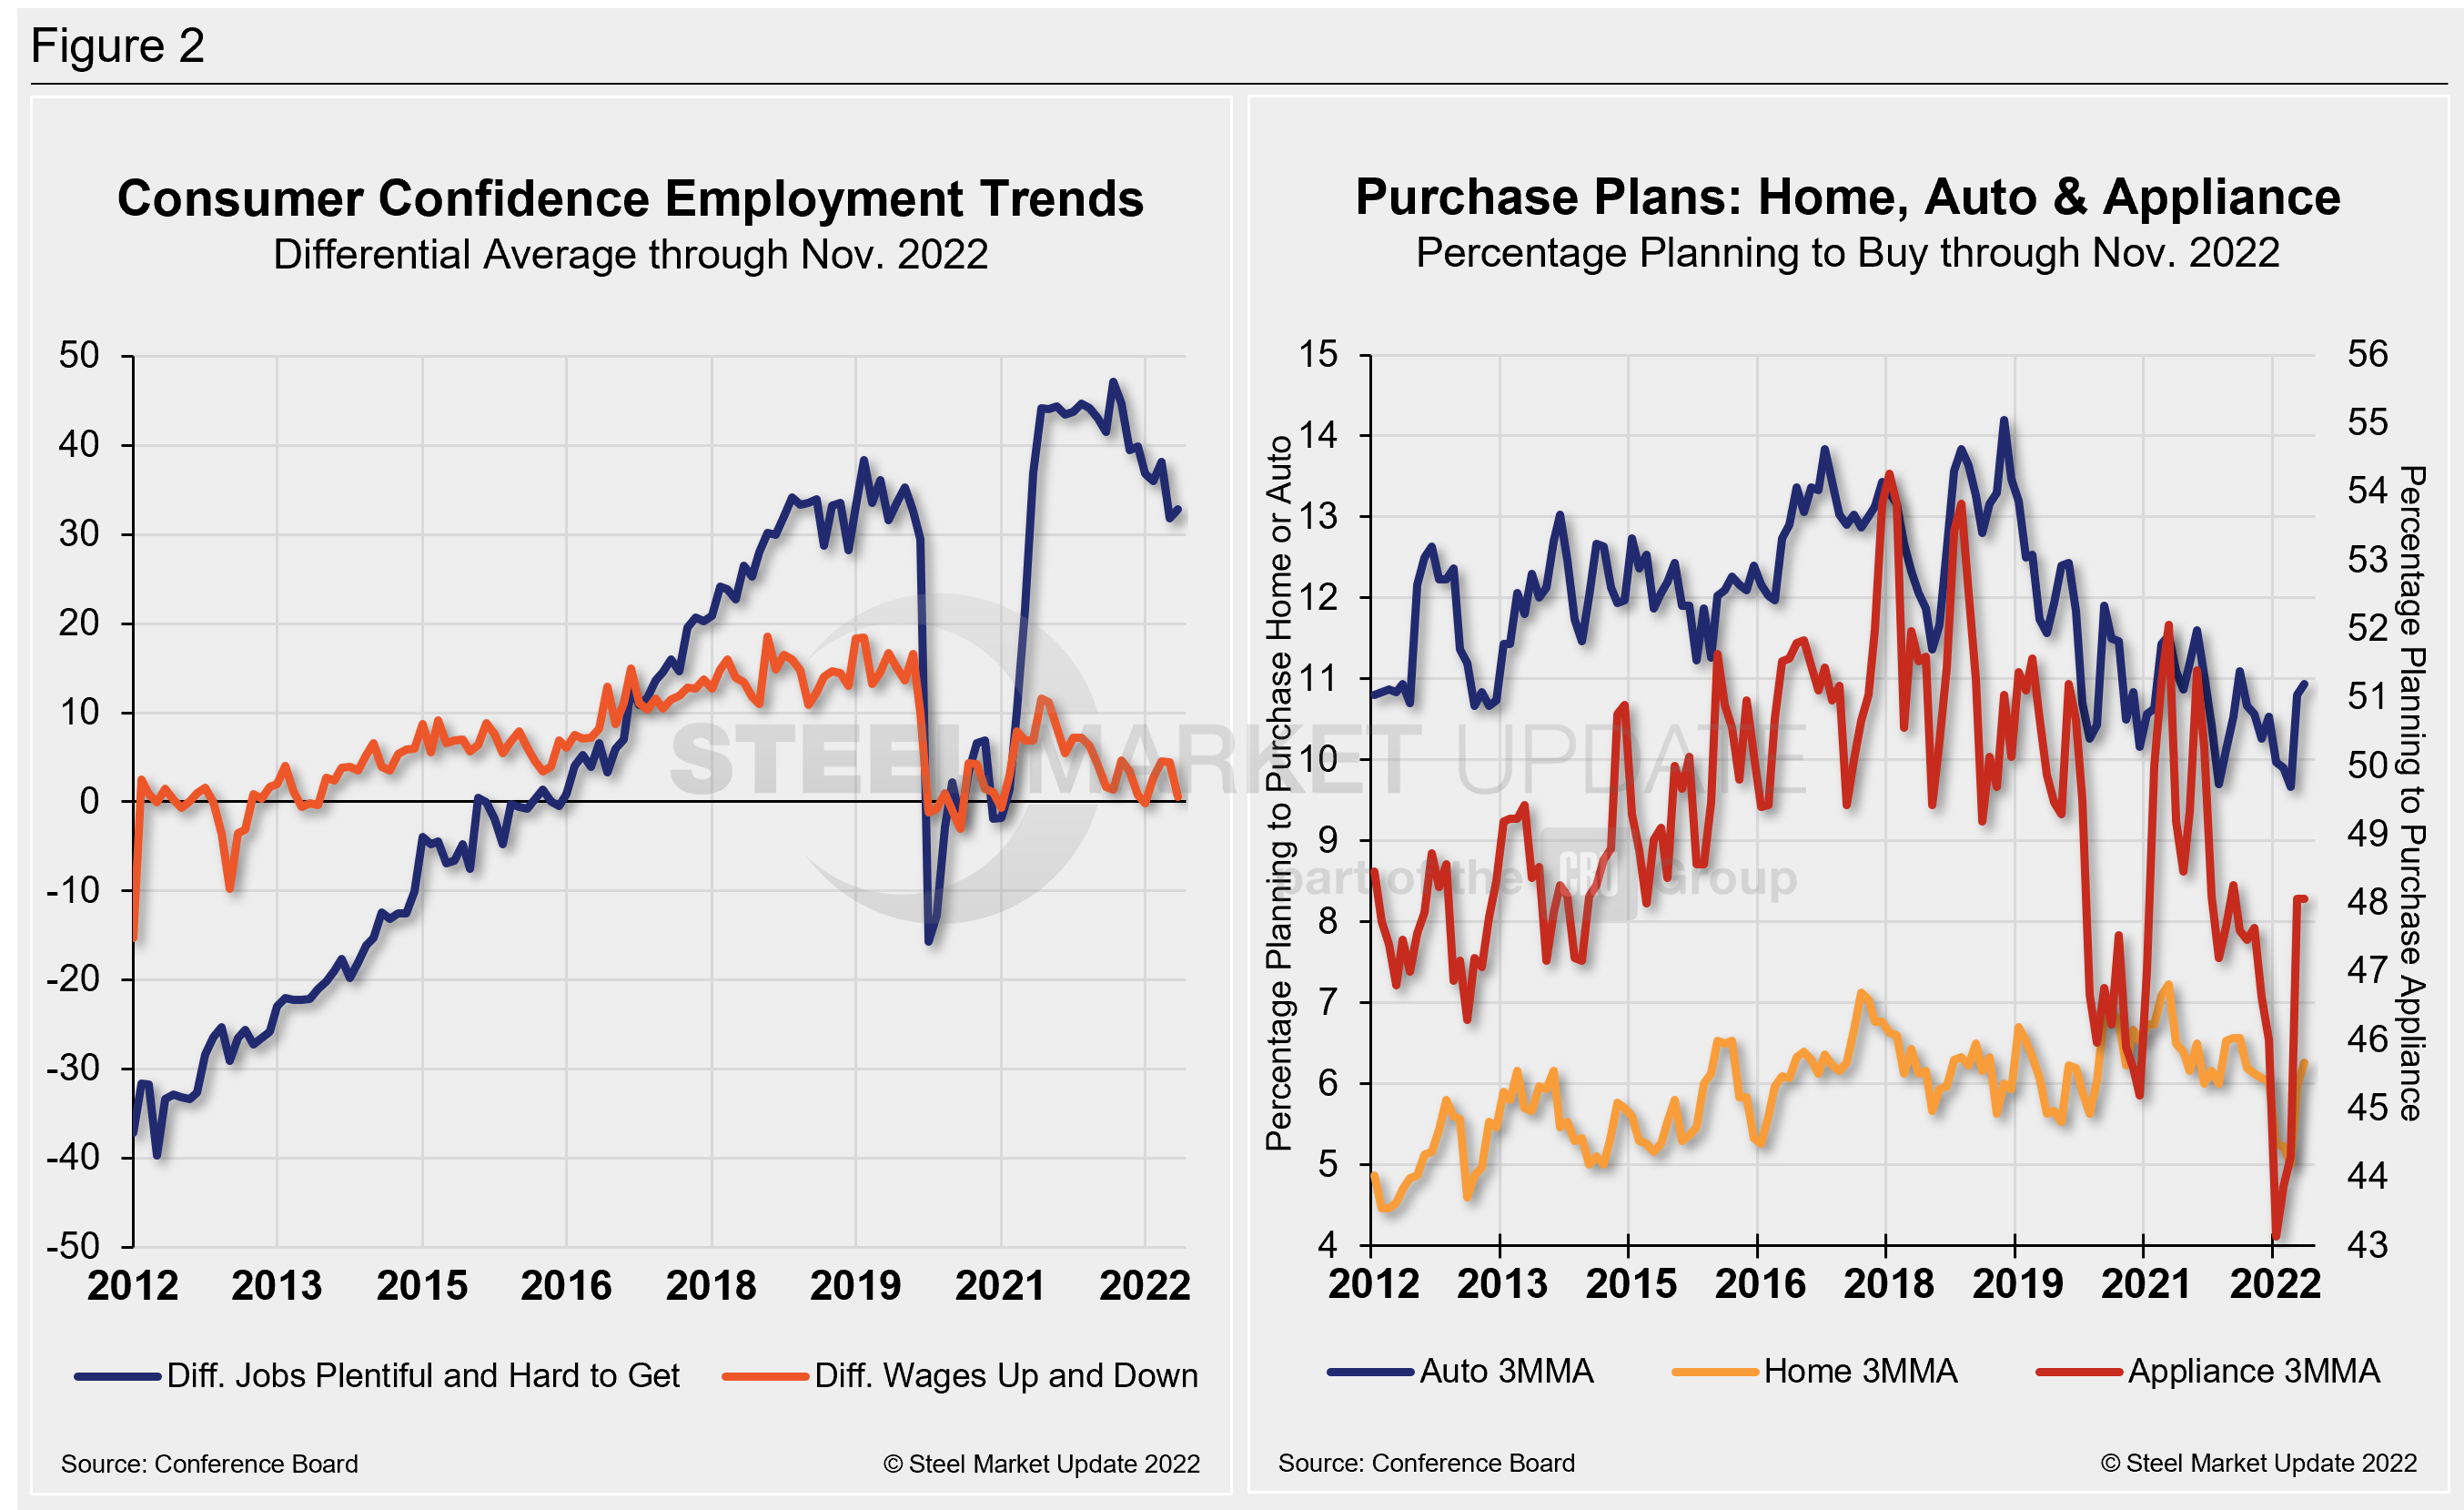
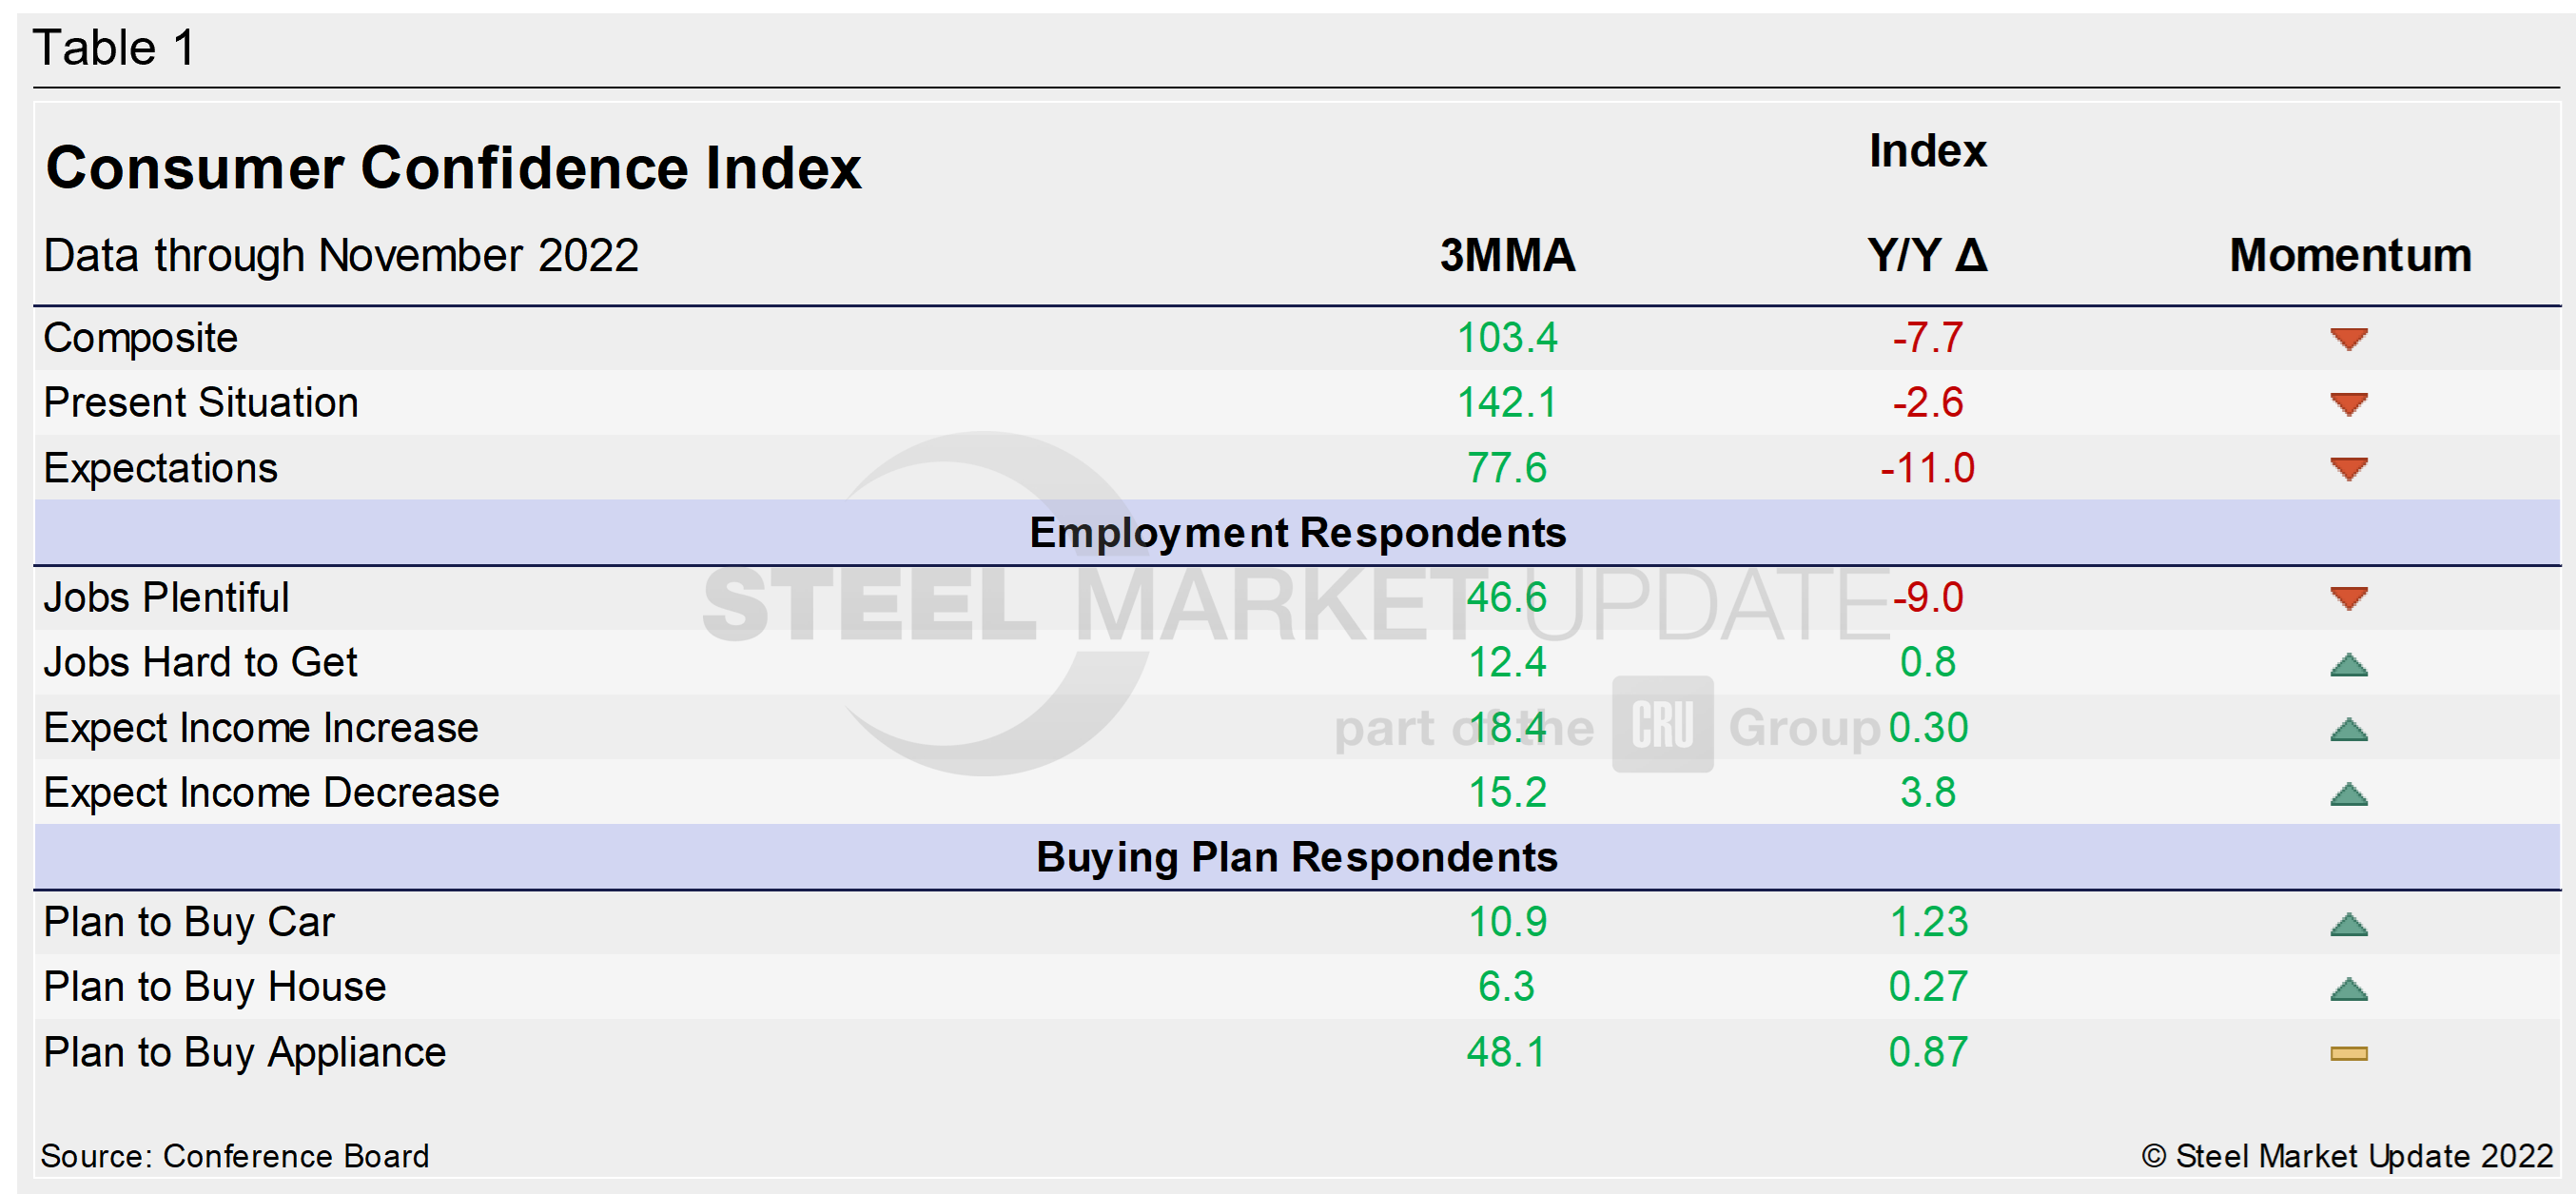 People found jobs more plentiful in November but were far less optimistic about wage increases compared to the month prior. The differential between those finding jobs and those having difficulty was 32.8 in November, up from 31.8 in October. The measure is trending further way from the most recent pre-pandemic high of 44.1 seen just about a year ago. The difference between those expecting wages to rise versus those expecting wages to fall is 0.6, down 3.8 points MoM, and well removed from the recent high of 11.6 last June. Buying intentions for big-ticket items — cars, homes, and major appliances — were all down in November. Consumers continue to worry about the economy’s outlook, showing less interest in buying big-ticket items over the next six months, and they also pulled back on travel plans, the report said. The share of consumers planning to buy motor vehicles slipped 2.9 points MoM in November after increasing to the highest level last month since July 2020. Fewer consumers planned to buy appliances such as refrigerators and washing machines. Consumers were also less inclined to buy a house, as interest rates continue to rise amid high inflation. Auto buying saw the largest percentage decrease in November, down 22.5%, followed by major appliance buying (-14.1%), while home buying was down 13.5% over the same period. These recent dynamics and historical movements are illustrated below in Figure 2.
Note: The Conference Board is a global, independent business membership and research association working in the public interest. The monthly Consumer Confidence Survey®, based on a probability-design random sample, is conducted for The Conference Board by Nielsen. The index is based on 1985 = 100. The composite value of consumer confidence combines the view of the present situation and of expectations for the next six months.