Commerce raises AD duties on Korean OCTG
The US Commerce Department has raised the anti-dumping duties (AD) on imports of oil country tubular goods (OCTG) from South Korea.
The US Commerce Department has raised the anti-dumping duties (AD) on imports of oil country tubular goods (OCTG) from South Korea.
After an annual administrative review, the Commerce Department increased the anti-dumping duties on large-diameter welded pipe from Turkey.
Steel market chatter this week Earlier this week, SMU polled steel buyers on an array of topics, ranging from market prices, demand, and inventories to tariffs, imports, and evolving market events. We are sharing a selection of the comments we received below, in each buyer’s own words. Before diving in, we reviewed all of the responses collected and compiled these key takeaways: • Most buyers continue to expect higher prices in the near future and report that demand is stable to improving. • Inventories are moving faster than they were this time last year for most respondents, attributed to limited availability and leaner supply chains. • Imports are attractive for many buyers on both price and availability, though quotas, long lead times, and quality concerns continue to limit their appeal. • Buyers were split on whether tariff policies are helping their businesses, while a slight majority reported some evidence of manufacturing reshoring, though many said it is still too early to tell. Want to share your thoughts? Contact david@steelmarketupdate.com to be included in our market questionnaires. How do you expect prices to trend over the next three months? “I expect prices to rise at a fairly rapid pace for at least the next two to three months because inventories will continue to decrease.” “Upward, capacity remains tight.” “Climbing for several months.” “Trending toward $1,300/st HRC, only because one small player is driving prices up with no one else selling spot.” “Higher, the Q1 bump is not showing in the futures market.” “We expect things to keep going up from here. Next year could get ugly, but we're not there yet.” “Still trending up. There are some soft spots getting softer, but still steady demand and a shortage of supply.” “Continue to rise slowly.” “Slow increases like they have been doing.” “Upward due to continued demand and mill maintenance outages.” “Will remain high but steady due to demand and tariff implications.” “Plate prices most likely will be flat to up over the next three months.” Is demand improving, declining or stable? “Demand is stable (if anything, overstated), with inventories so lean, late mill deliveries, and contract prices increasing next year.” “Demand is fairly consistent with the rest of the year.” “Stable, but very strong for our products.” “Stable as many projects are trying to get ahead of potential additional price increases.” “Stable due to the ‘slow season’ in our market.” “Plate demand is stable to improving.” “Demand is good to improving. We'll take it!” “Improving, but still not to 100% capacity.” Is inventory moving faster or slower than this time last year? “Faster... once it arrives (late), it goes right back out.” “Faster due to lack of availability and bullwhip buying.” “Inventory is moving faster this year than last because demand is stronger than last year and many of our competitors don't have as much steel to offer.” “Inventory is moving faster with supply chains so lean.” “Inventory is moving at a good clip. Just based on costs/spends, we're stocking less sheet, coil and plate though.” “Plate inventory is moving at a much faster pace year over year due to several factors.” “Faster due to a shortage of supply plus added demand.” “About the same.” Are President Trump's tariff policies helping your business? Buyers were split this week, with 44% believing the tariffs are helping their business and 44% saying they are not. The remaining 11% were unsure how the policies will impact them. Comments included: “Yes for now. Prices are very high, which causes people to buy before prices get higher.” “Yes, I credit Trump's policies and data centers for improving demand.” “Yes, inventory values continue to go up.” “They are helping on the sell side and hurting on the buy side.” “No, they are creating shortages and increasing the cost of steel.” Are you seeing evidence of manufacturing reshoring to the US because of Trump's tariffs? The slight majority of respondents (39%) reported they have seen some evidence of reshoring, a higher rate compared to recent surveys. A third said it is too early to say, and 28% answered they are not seeing any signs of reshoring. Comments included: “Yes. Perhaps reshoring has added to the increased demand in 2026.” “Yes, with machining and turning.” “Yes, capacity versus demand in North America is creating pressure to reshore products.” “Too early to say. There have been a lot of announcements, but steel availability has limited immediate moves.” Are imports more attractive than domestic material? “Imports are more attractive on a pricing front and an availability standpoint, but lead times are extended.” “Imports are attractive in both price and because they offer additional availability. Whether or not they show up and or as offered is another issue.” “Imports are certainly attractive. They're coming in in earnest, so this run will peter out early next year.” “Attractive due to price and availability.” “Attractive, domestic tons are unavailable.” “Yes on light gauge painted.” “Without quotas, yes, the price is more attractive. But if you get caught with the quota, pricing is very high.” “Not to us, but we are hearing more about affordable imports.” “Plate imports are only slightly more attractive than domestically produced plate.” “Not yet, shipping lag is still too large.” “No due to tariffs.” What's something that's going on in the market that nobody is talking about? “What is the latest on SDI/BlueScope? I had heard it was back on the ‘front burner’ but all is quiet now. Maybe that means a deal is getting close?” “Will the US bring a trade case against South Korea over imports spiking?” “Busheling scrap prices are flat, while hot roll continues to rise. The scrap gap is increasing.” “How will the next administration handle tariffs that have so limited our steel supply?” “Mill discipline in production capacity.” “Coke pricing levels due to demand and supply.” “Shipbuilding.”
The US Department of Commerce has preliminarily determined that critical circumstances exist in the countervailing duty (CVD) investigation of imports of large-diameter graphite electrodes (LDGEs) from China.
The phrase “Fortress North America” seems to resurface anytime US, Canada, and Mexico trade negotiations roll around. The idea of an economic Fortress North America burst onto the scene in the late 1980s and early 1990s in the lead up to NAFTA. In theory...
The Commerce Department has found high dumping rates of Chinese tin mill products in the US market.
In the trade case investigating subsidized wire rod imports from Algeria, the Commerce Department set final subsidy rates and officially issued the countervailing duty (CVD) order.
The US Department of Commerce has raised the anti-dumping duties (AD) on imports of oil country tubular goods (OCTG) from Vietnam.
United Steelworkers (USW) International President Roxanne Brown urged US and Canadian trade representatives to reach an agreement that puts working families first. Her words come as trade talks between the two nations remain at an impasse, and escalating tensions have led to new tariffs on both sides. “This conflict is hurting jobs. It’s hurting facilities. It’s hurting communities. And it’s creating uncertainty for workers and families in both countries,” Brown said at a press event on Tuesday.
A policy that protects steel production while making downstream American manufacturing less competitive internationally merely moves the injury along the domestic supply chain.
US steel imports increased 7.8% in July and, based on US Department of Commerce license data, rose even higher in August.
China is bumping up against its official primary production capacity limit of 45.3 million metric tons/year, but production can still increase through “capacity creep.”
If the question is, “Brother, can you spare a spot ton?” The answer from many mills might be “No.” Or perhaps, in the case of hot-rolled (HR) coil, “Do you have $1,300 per ton?”
Canada’s retaliatory tariffs on US goods have drawn support from Canadian steel producers and labor groups. Meanwhile, US manufacturers and trade officials are calling for renewed negotiations as the dispute adds costs and uncertainty to cross-border supply chains.
The retaliatory measures—which include 50% tariffs on US steel and aluminum—came after trade talks between Washington and Ottawa collapsed last month.
Rather than recruiting other countries to help, the US appears intent on threatening to punish countries, including its closest friends. In my experience, this strategy has never proved productive.
Panelists on the trade panel at SMU Steel Summit 2026 reflect on issues affecting the industry.
First, a big thank you to everyone who attended SMU Steel Summit this week and the inaugural AMU Aluminum Summit as well. I’m not going to crow too much about it being another record year in terms of attendance. But it was—and you made that possible. Also, it’s always great to see the entire steel […]
SMU’s average price for domestic hot rolled (HR) rose to $1,200 per short ton (st) week on week (w/w). In offshore markets, prices also rose, outpacing stateside gains.
Canada has moved to impose new tariffs on US goods, matching tariffs the US has imposed on it.
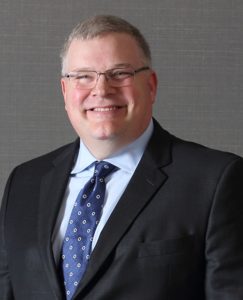
Barry Schneider, Steel Dynamics’ president and COO, and chairman of the Steel Manufacturers Association (SMA), said transshipment is a central trade policy concern. Speaking during a fireside chat Monday afternoon at the SMU Steel Summit 2026 in Atlanta, he identified steel, fabricated products, and pipe as areas exposed to potential leakage through the two USMCA partners.
SMU’s average price for domestic hot rolled (HR) rose to $1,195 per short ton (st) week on week (w/w). In offshore markets, prices saw a more controlled rise.
A trade deal between the US and Canada is reportedly pending that could halve Canada’s Section 232 steel and aluminum tariffs and see automobile tariffs lowered from 25% to 15%.
SMU’s average price for domestic hot rolled was unchanged week on week at $1,180 per short ton. In offshore markets, prices mainly moved up.
US steel exports recovered 7% in June, marking the highest monthly rate recorded since January 2025. Despite the recoveries seen over the last six months, trade has been historically weak for over a year and remains weak compared to 2022-2024 volumes.
Licenses to import steel into the US surged in July to the highest level since June 2025, according to recently released US Commerce Department data. Final June figures show a 3.8% month-on-month decline, while July licenses show a 9% recovery.
The US-flag Lake Carriers Association reported steady iron ore trade on the Great Lakes in July.
This CRU insight is the third installment on how El Niño may impact the steel and steelmaking raw materials markets.
It’s tough to find a new angle to write about in a market that continues to be characterized by the same trends. You know the ones: extremely limited spot tons, long lead times, low inventories, and high prices.
SMU’s average price for domestic HR rose to $1,180 per short ton (st) this week, $15/st higher vs. the prior week. In offshore markets last week, prices mainly moved up.