• Skip to main content

    Market Segment

    US HRC, Busheling Scrap Price Spread Narrows in August

    Written by Ethan Bernard


    The spread between hot-rolled coil (HRC) and prime scrap prices narrowed further this month, according to Steel Market Update’s most recent pricing data.

    SMU’s average HRC price dropped, while busheling scrap tags ticked up slightly into a wider range.

    Our HRC average price fell $15 per net ton week over week to $790 per ton ($40 per cwt) as of Tuesday, Aug. 8. 

    Busheling tags, however, increased $5 per gross ton from July to an average of $450 per gross ton for August. Figure 1 shows price histories for each product.
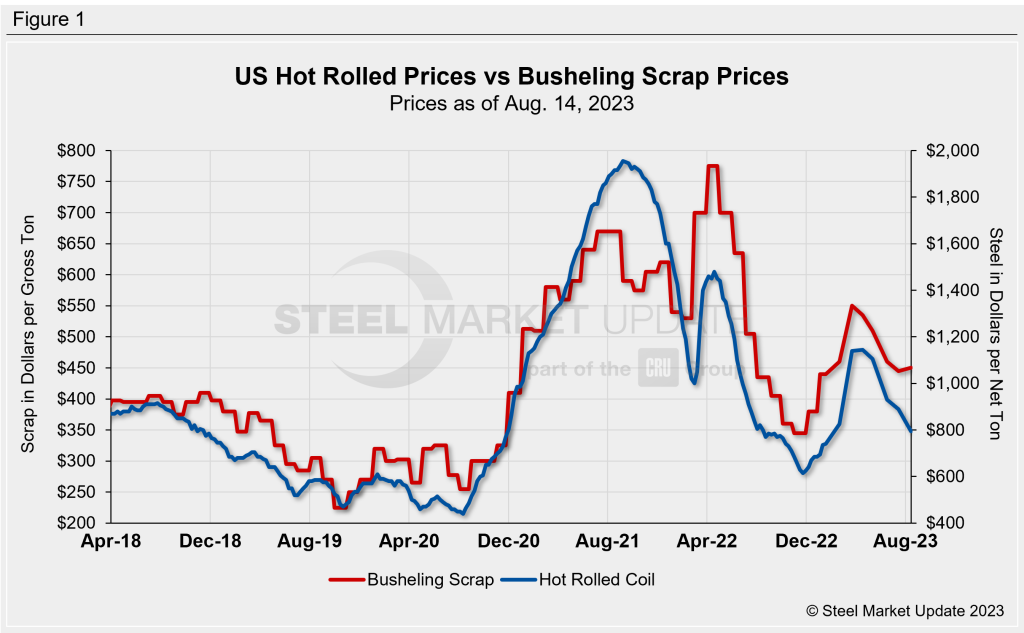
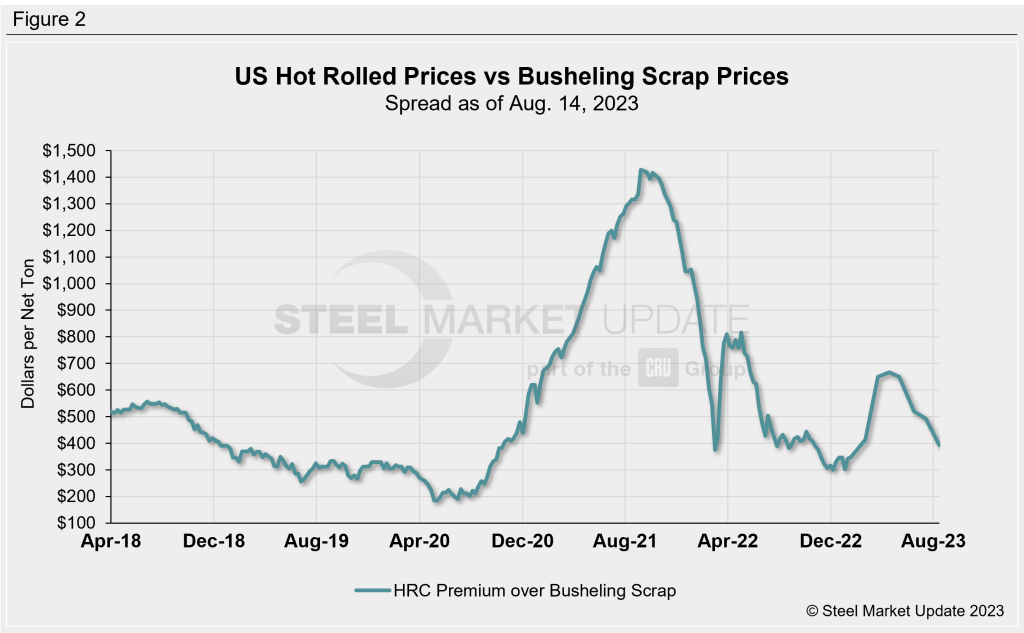
    After converting scrap prices to dollars per net ton for an equal comparison, the differential between HRC and busheling scrap prices is $393 per net ton as of Aug. 14, down $100 from a month earlier. (Figure 2). This is the fourth consecutive month where the spread has narrowed.
    By the way, did you know our Interactive Pricing Tool has the capability to show steel and scrap prices in dollars per net ton, dollars per metric ton, and dollars per gross ton?

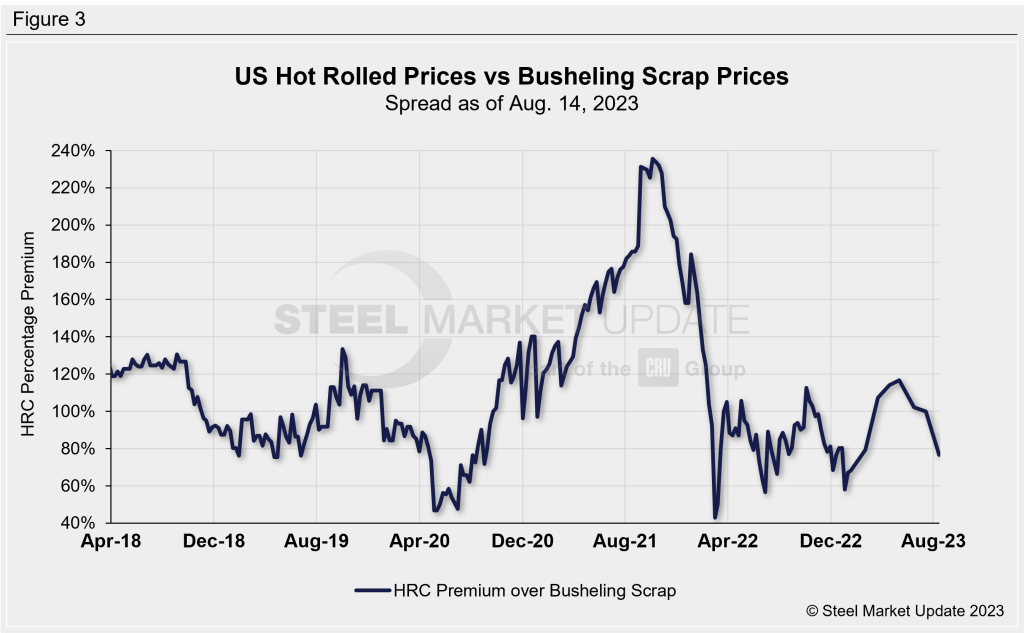
    Figure 3 explores this relationship in a different way – we have graphed HRC’s premium over busheling scrap as a percentage. HRC prices now carry a 77% premium over prime scrap, off from 100% a month earlier.
    Ethan Bernard

    Read more from Ethan Bernard

    Latest in Market Segment

    Price on trade: Steel industry trick-or-treat

    It’s the scariest time of year in Washington, D.C. … election season. The city is a veritable haunted house of prognostication and speculation as everyone tries to discern which way the howling wind will blow. We’ll let the fortune tellers and prediction markets guess the outcomes of the midterms. What we do know is this: the steel industry has experienced its share of tricks and treats over the past few months. Below are a few notable steel tricks and treats this Halloween season.

    Drilling activity holds in the US, moves higher in Canada

    The latest tally of active drilling rigs held steady in the US for a fourth straight week, while activity rose further in Canada this week, according to oil and gas rig count data published by Baker Hughes. The US rig count remained unchanged at 603 rigs this week, maintaining a 17-month high. Compared with this time last year, 57 more rigs are in operation today. Canada’s count rose by six to 226 rigs this week, gaining ground for a second consecutive week. Activity is up from the same week of 2025, with 39 more rigs operating today.

    galvalume steel coil

    SMU Survey: Mill willingness to negotiate price at lowest levels since 2021

    The majority of steel buyers responding to our latest market survey reported that mills continue to hold a firm grip on prices. The share of buyers reporting that mills were negotiable fell this week to the lowest rate seen in over five years. Every two weeks, SMU surveys service center and manufacturer buyers asking if mills are negotiable on new spot sheet and plate orders. In this week’s survey, just 3% of respondents said mills were willing to talk price to secure an order (Figure 1). This is down 11 percentage points from our mid-October survey.

    Algoma’s losses narrow in Q3, but tariffs and EAF transition challenges remain

    Algoma’s net loss narrowed in the third quarter, but the company continues to be affected by US tariffs and the transition to electric-arc furnace (EAF) steelmaking. The Sault Ste. Marie, Ontario-based steelmaker reported a net loss of Canadian $129.6 million (USD$92.6 million) in the third quarter ended Sept. 30, narrowing 73% from CAD$485.1 million a year earlier. Net sales dropped 52% to CAD$249.4 million in the same comparison.