Prices
September 23, 2021
Futures: Iron Ore – Selling Pressure Continues!
Written by Tim Stevenson
SMU contributor Tim Stevenson is a partner at Metal Edge Partners, a firm engaged in Risk Management and Strategic Advisory. In this role, he and his firm design and execute risk management strategies for clients along with providing process and analytical support. In Tim’s previous role, he was a Director at Cargill Risk Management, and prior to that led the derivative trading efforts within the North American Cargill Metals business. You can learn more about Metal Edge at www.metaledgepartners.com. Tim can be reached at Tim@metaledgepartners.com for queries/comments/questions.
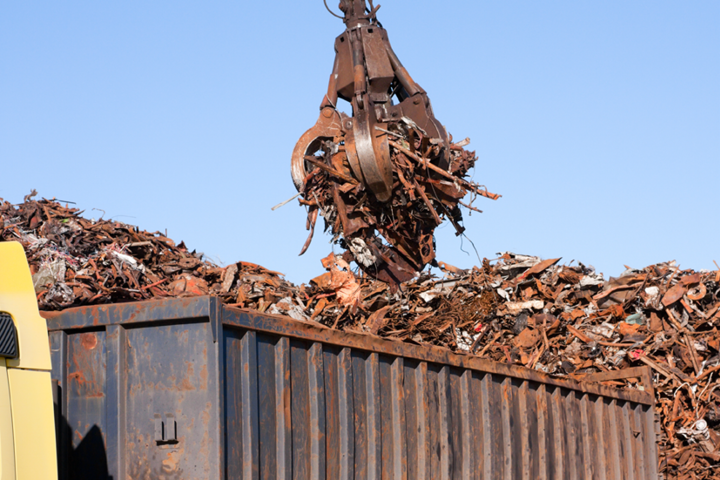
Iron ore is of course one of the key raw materials for steelmaking. Blast furnaces combine ore with a number of other ingredients (including coke which is made from metallurgical coal) to make steel. While minimills don’t use ore directly – scrap is really just ore and energy combined. Consequently, at the end of the day, ore prices matter for all steel production costs.