Prices
December 20, 2023
Miller on scrap: 2023 in review
Written by Stephen Miller
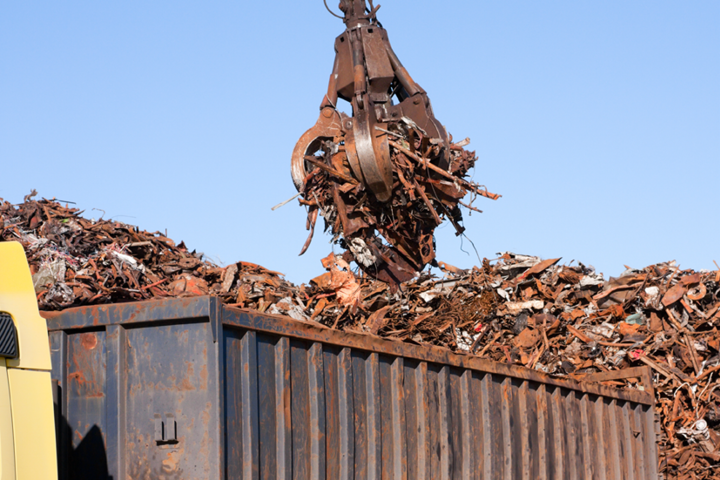
As we look back at the scrap market for 2023, it basically followed its normal seasonal pattern. Most of the disruptive geopolitical events that riled ferrous raw materials occurred in 2022. So, with those things out of the way—or settling down at least for now—2023 resumed its normal pattern. Ferrous scrap rose in Q1 from the lower prices we saw in Q4’22. It peaked in April as scrap flows recovered from winter hibernation.
After April, prices started their slow and steady decline for the next six months, except for a brief rise for shredded in June. The price drop ended in October with prime scrap still falling and obsolescent grades trading sideways. After this, the market rose with emphasis on prime grades, largely due the automotive strike and increased mill demand after several outages in Q3 and Q4. Prices for imported pig iron bottomed in October, and this had a bullish effect on scrap prices, as prime grades rallied well over $120 per gross ton (gt).