SMU Survey: Current, Future Sentiment Indices slip
SMU’s Steel Buyers’ Sentiment Indices edged down this week, according to our most recent survey data.


SMU’s Steel Buyers’ Sentiment Indices edged down this week, according to our most recent survey data.
SMU’s latest steel buyers market survey results are now available on our website to all premium members.
The pig iron import market in the US continues its upward price movement.
Steel mill lead times remain at or near multi-year highs for all sheet and plate products.
This week we saw low negotiation rates across all products, with coated and plate products slightly more negotiable than hot rolled and cold rolled.
Market participants report frustration with extending lead times for domestically produced plate products.
Volume, which is usually a big positive for buyers in price negotiations, has arguably become a net negative.
Sheet and plate price indices increased between $5-20 per short ton (st) from last week.
SMU’s Mill Order Index (MOI) eased marginally in April, losing some momentum after moving higher in March.
The export markets are generally showing an increased demand for scrap.
This long weekend, we pay tribute to the sacrifices of the men and women of the US armed forces.
Domestic plate market participants named extended lead times, increased freight costs, escalating fuel surcharges, and spotty demand as their most recent challenges.
Earlier this week, SMU polled steel buyers on an array of topics, ranging from market prices, demand, and inventories to tariffs, imports, and evolving market events.
Galvanized steel buyers and distributors expect tightening supply and rising price pressure to last into summer.
We look at how SMU survey respondents are seeing the effects of Trump's tariffs and the Iran war on business.
Sheet prices continue to rise in a market that remains characterized by extremely limited spot availability, solid demand, long lead times, and the lowest sheet inventories since May 2021.
SMU spoke with several market players around the country regarding the ferrous scrap market in June, with many sources seeing next month as broadly sideways.
Trading-company sentiment in the May 15 SMU flat-rolled steel buyers survey shows a market split between anecdotal optimism and numerical decline.
The Commerce Department's International Trade Administration recently concluded several administrative reviews of the anti-dumping and countervailing duties (AD/CVDs) on various steel imports. The reviews resulted in the following duty adjustments.
Domestic raw steel production ticked up to the highest weekly output rate recorded since March 2020, according to recently published American Iron and Steel Institute (AISI) data.
Grupo Acerero SA de CV posted higher shipments and stronger profitability in the first quarter of 2026.
Apparent steel supply surged 11% from February to March, recovering from one of the lower rates recorded in recent years to one of the higher ones.
SMU released its latest steel market survey results on Friday. The main takeaway: the stronger for longer narrative is still very much in the house.
Unsurprisingly, the Trump-Xi Beijing summit ended without a major announcement on trade. Behind the celebratory mood and photo-ops are years of economic harm from China’s predatory trade practices that cannot be overcome in a single meeting.
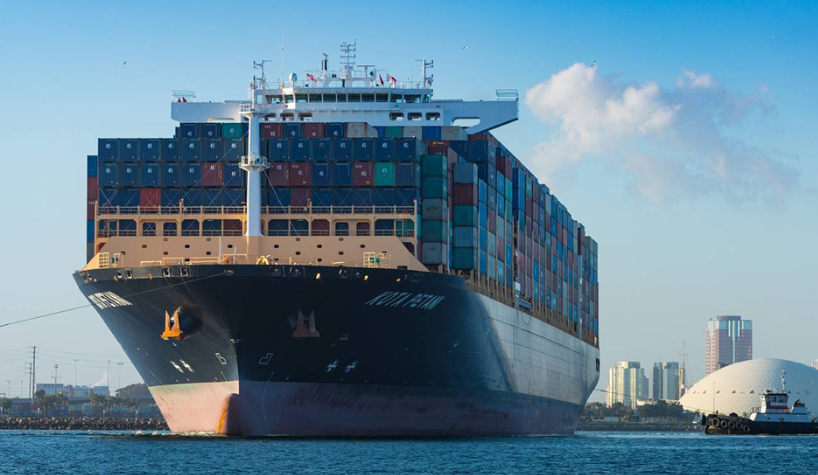
Sources told SMU they’ve begun considering whether US imports of sheet might benefit the overall market.
Global shipping volatility is tightening its grip on steel supply chains. And the risks are not easing; in fact, they’re escalating, according to Anton Posner, CEO of Mercury Resources.
The spread between domestic hot-rolled coil and prime scrap prices continued to widen in May, a trend that began in September.
SMU’s latest steel buyers market survey results are now available on our website to all premium members.
SMU’s Steel Buyers’ Sentiment Indices remained in strongly optimistic territory this week, based on responses from steel executives in our latest market survey.
US service centers’ flat-rolled steel supply fell for a fourth straight month in April, with shipping days of supply slipping to 45.7 on an adjusted basis, according to SMU data.