Steel market chatter this week
Earlier this week, SMU polled steel buyers on an array of topics, ranging from prices, demand, and inventories to tariffs, imports, and evolving market conditions.


Earlier this week, SMU polled steel buyers on an array of topics, ranging from prices, demand, and inventories to tariffs, imports, and evolving market conditions.
Manufacturing activity in New York state increased modestly in June, easing after posting strong growth the month prior, according to the Empire State Manufacturing Survey.
SMU’s average price for domestic HR was $1,130 per short ton (st) this week, $15/st higher week over week (w/w). In offshore markets last week, prices were largely down, following a trend seen since late April.
SMU’s Steel Demand Index ticked back up from late May, remaining in elevated territory, according to mid-June indicators.
The spread between domestic hot-rolled coil and prime scrap prices continued to widen in June, a trend that began in September.
SMU’s Mill Order Index recovered in May, reclaiming some momentum lost the month prior.
Ferrous scrap prices for June came in sideways, scrap sources told SMU.
SMU released May service center inventories on Monday. And if you’re a premium subscriber, I recommend reading the report (here) if you haven’t already.
SMU’s sheet price indices increased further this week, while plate held steady, all at multi-year highs.
Apparent steel supply eased from March to April on reduced mill shipments per recent Department of Commerce and American Iron and Steel Institute (AISI) data.
The scrap market seems firm as we go into the midsummer month of July without too many changes from June.
US steel exports improved 2% from March to April to the highest monthly volume seen in 13 months. Although up, trade remains historically low
SMU’s June 12 Flat-Rolled Steel Buyers’ Survey shows a divided steel community on the effects of President Trump’s tariff policies, emerging but uneven signs of reshoring, and near-universal cost pressures tied to the Iran conflict.
Total heating and cooling equipment shipments declined 5% in April, according to AHRI figures.
US service centers’ flat-rolled steel supply declined for a fourth straight month in May, with shipping days of supply slipping to 44.7 on an adjusted basis, according to SMU data.
Summer doldrums? Not this year! SMU’s latest steel market survey indicates that an increasing number of steel buyers think prices will continue to rise along with the mercury.
The Trump tariffs have driven the mundane world of traditional “trade remedies” off the front pages. But antidumping and countervailing duty measures are still with us, and new cases are on the upswing lately.
In just a little over two months, the flat-rolled steel industry will gather in Atlanta to uncover the decisions, innovations, and forces shaping the market today — and what’s coming next.
Friedman Industries posted record sales, higher volumes, and sharply improved earnings in fiscal 2026. This was driven by stronger demand, higher average selling prices, and continued contributions from its Century Metals acquisition.
After reaching historic lows late last year, import volumes have increased each month of 2026, according to recently released US Commerce Department data.
SMU’s latest steel buyers market survey results are now available on our website to all premium members.
SMU’s Steel Buyers’ Sentiment Indices remained strongly optimistic this week and continue to indicate that buyers are confident in their companies’ prospects.
The World Cup only comes around every four years. So let's take a walk down memory lane to see where the steel market stood four years ago.
A major trade case finalized late last year, along with higher Section 232 tariffs, account for the reduced imports.
Steel mill lead times extended this week on both sheet and plate products, now at multi-year highs.
One possible reason for the lull in activity is the ambiguity of the tariff treatment of Brazilian pig iron following an announcement last week from the Office of the US Trade Representative (USTR) about Section 301 tariffs.
This week we saw continued low negotiation rates across all products, with cold rolled and plate the least negotiable and galvanized the most.
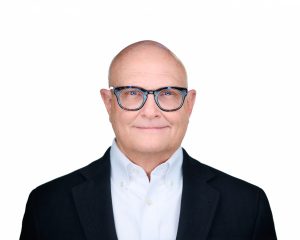
Gregg Troian, industry veteran and president of both PGT Trucking and the Board of Directors at the American Transportation Research Institute, cautions that the trucking industry continues to face mounting obstacles.
The Office of the US Trade Representative has proposed a Section 301 tariff carve-out for direct-reduced iron (DRI) and hot-briquetted iron (HBI) from Brazil while planning higher tariffs for other major suppliers.
The price gap between US hot-rolled coil (HR) and landed offshore product continues to narrow, as stateside prices are now, on average, carrying a premium over imports. Domestic tags are still outpacing imported hot band as pricing dynamics diverge.